Trusted by 3000+ clients

Sole Trader Trailer Finance

Running your own business? Get trailer finance that works for you.

Whether you're an owner-driver buying your first trailer, a civil contractor upgrading equipment or an established sole trader adding another asset, TAFS can help you explore finance options suited to your business.

We work with sole traders across Australia, with access to more than 80 lenders for new and used commercial trailer finance.

Sole Trader Trailer Finance

Trailer finance for Australian sole traders

Sole trader trailer finance is commercial asset finance used by individuals operating a business as a sole trader to purchase trailers for business purposes.

Sole traders can apply for finance across a broad range of commercial trailers, including assets purchased through dealers, private sellers and auctions.

Unlike a company, a sole trader operates their business as an individual. That means lenders generally consider the individual's financial position and business circumstances together.

The finance available will depend on the applicant's trading history, income, credit profile, existing commitments and the trailer being purchased.

TAFS reviews these factors before approaching lenders so the application can be matched with suitable finance options. See the full range of commercial trailer finance options.

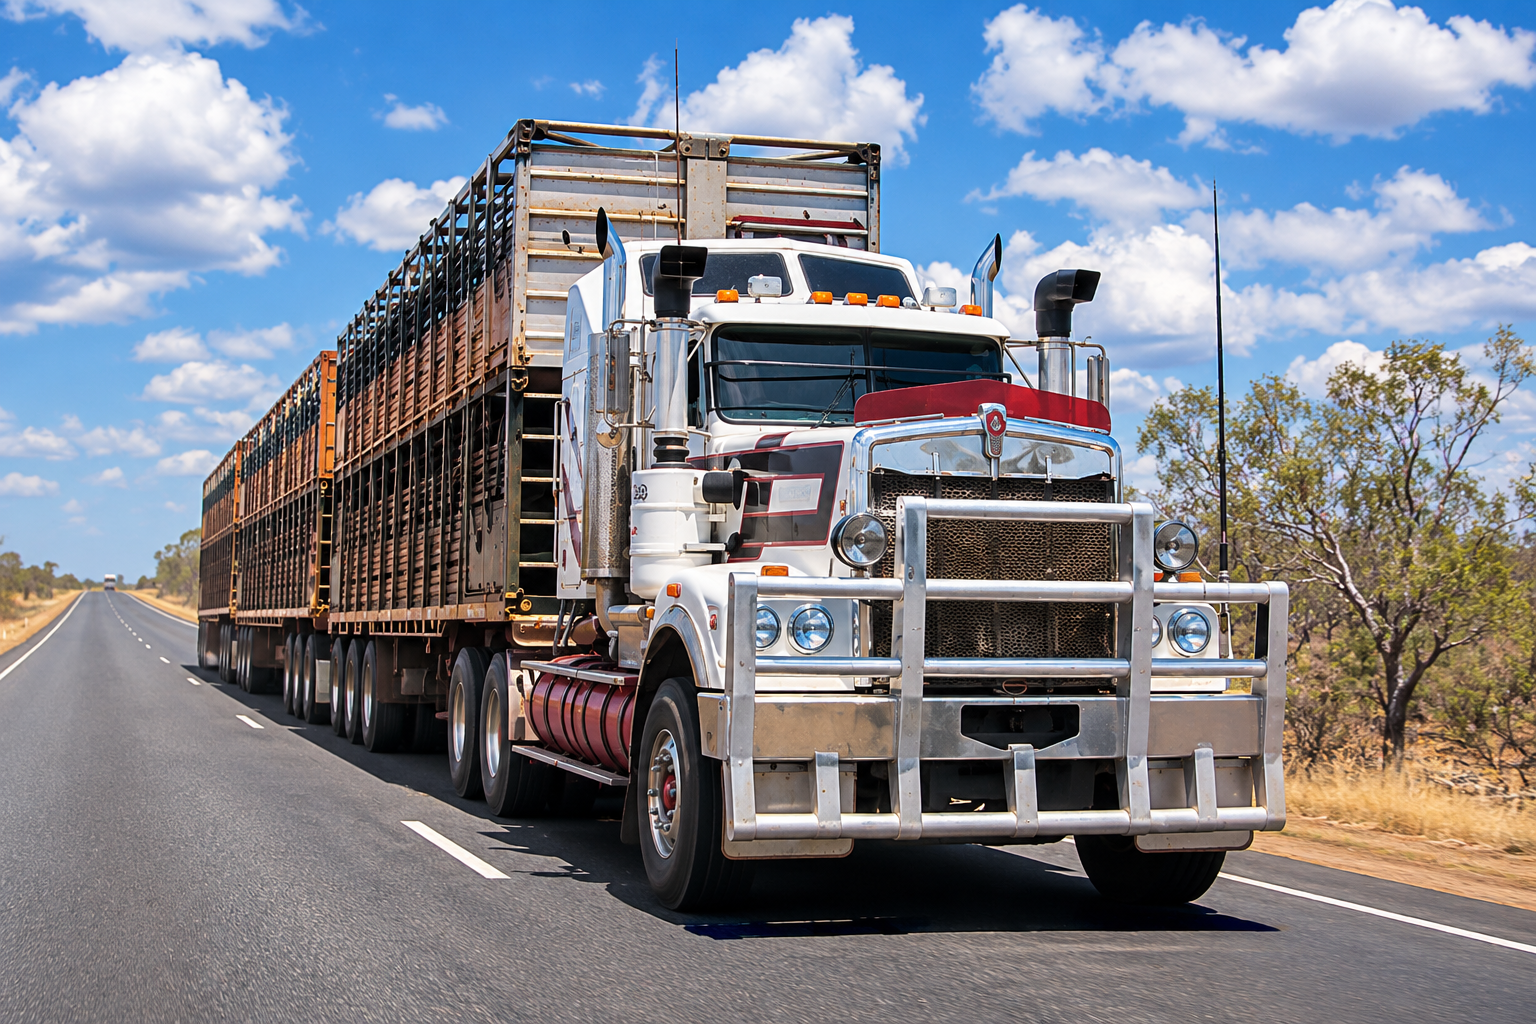
Maroon road train on an outback highway

Can a sole trader get trailer finance?

Yes. Sole traders can apply for commercial trailer finance, subject to lender requirements.

You don't necessarily need to operate through a registered company to finance a commercial trailer.

Some lenders have different policies for sole traders compared with companies.

TAFS reviews the overall application to identify lenders suited to your business structure and financial position.

A lender may consider:

  • ABN registration
  • Business trading history
  • Industry experience
  • Business income
  • Personal financial position
  • Credit history
  • Existing debts
  • Trailer age and value
  • Deposit or trade-in

How sole trader trailer finance works

How sole trader trailer finance works

Sole traders operate under their own legal identity, even where they use a registered business name. For finance purposes, the lender generally assesses the individual carrying on the business. This can involve reviewing both business and personal financial information.

For example, an established owner-driver may have consistent business income but also personal commitments such as a home loan or other credit facilities. Those commitments can form part of the lender's affordability assessment.

TAFS reviews the business, individual applicant and proposed trailer before recommending suitable options.
Sole trader finance isn't the same as company finance

Both sole traders and companies can apply for commercial trailer finance, but their legal structures differ. A company is a separate legal entity. A sole trader carries on the business as an individual.

This distinction can affect who enters the finance agreement, how the lender assesses income, what identification is required, which financial commitments are considered and how the trailer purchase is documented.

The lender's specific requirements depend on the finance product and applicant. TAFS can help explain what information is needed for a sole trader application.

Buying your first trailer as a sole trader?

Purchasing your first commercial trailer can be a major step.

You may already own or finance a prime mover but currently rely on hired trailers or equipment supplied by customers.

The lender may consider your previous industry experience, current income, existing truck finance and expected work.

TAFS reviews the complete application rather than focusing only on whether you've previously owned a trailer.

Buying your own trailer can give you more control over:

  • Trailer availability
  • Freight opportunities
  • Work scheduling
  • Equipment configuration
  • Operating capacity

What trailers can sole traders finance?

TAFS can assess finance for a range of commercial trailers used by sole traders. This can include:

The trailer must meet the selected lender's requirements. Age, condition, purchase price and intended use can influence the available options.

  • 15,000+Assets Financed And Businesses Helped
  • $350M+Total Business Funding
  • 80+Lenders To Compare
  • 30+Years Of Business Experience
  • 93%Client Success Rate

Sole trader trailer finance by industry

Sole trader trailer finance for owner-drivers

Owner-drivers often operate as sole traders in the Australian transport industry. You may be purchasing your first trailer, a replacement trailer, an additional trailer or a specialised trailer for new work.

Lenders can consider transport experience, the existing prime mover, business trading history, freight contracts, business cash flow, personal credit profile and current finance repayments.

Where the trailer will support existing or additional transport work, that commercial purpose can form part of the application.

Sole trader trailer finance for civil contractors

Civil and earthmoving contractors may operate as sole traders while owning trucks, machinery and other commercial assets.

A trailer purchase may be required to transport excavators, skid steers, construction materials, bulk materials or machinery attachments.

The lender can review the trailer alongside the contractor's existing equipment and work. TAFS can assess how the purchase fits into the wider business.

Sole trader trailer finance for agricultural businesses

Sole traders operating farming and agricultural businesses may require trailers for transporting machinery, produce and other commercial loads.

The lender may consider agricultural experience, existing equipment, business income, seasonal trading patterns, current finance commitments and the trailer purchase price.

Where income varies throughout the year, the finance structure needs to be considered alongside the business's cash flow. TAFS can review the individual business circumstances before identifying suitable options.

ABN, trading history and GST

Does a sole trader need an ABN for trailer finance?

Commercial trailer finance generally requires the applicant to be carrying on a business and to meet the lender's identification and eligibility requirements. An ABN is commonly part of the application.

The lender may consider how long the ABN has been registered and whether the business is actively trading.

TAFS can review your business details and explain the requirements relevant to your application.

How long does a sole trader need to be operating?

There is no single minimum trading-history requirement across every lender. Some lenders prefer businesses that have been operating for several years. Others may consider sole traders with shorter histories where the wider application meets their criteria.

Factors can include industry experience, business income, credit profile, deposit, existing work, and trailer age and value.

TAFS reviews these factors together when identifying suitable lender options.

Can a new sole trader get trailer finance?

Potentially. An individual may have years of relevant industry experience despite only recently registering an ABN. For example, a transport operator may have worked as an employee before becoming an owner-driver.

Some lenders may consider previous experience when assessing the application. However, a shorter trading history can limit the available options.

Does GST registration matter?

It can. Some lenders consider GST registration status as part of their eligibility criteria. Others assess the business using a broader combination of financial and trading information.

Not every lender applies the same requirements.

TAFS can review the ABN and GST position before identifying possible finance options.

How lenders assess sole trader income

How lenders assess sole trader income

Unlike a company, a sole trader's business income is generally assessed in the context of the individual operating the business.

A lender may request information showing business revenue, business expenses, taxable income, cash flow, existing loan repayments and other financial commitments. Depending on the lender, this may include tax returns, financial statements, BAS or bank statements.

The lender needs to be satisfied the proposed trailer repayments are affordable. TAFS can review the available financial information and recommend an appropriate application pathway.

What if your income varies each month?

Some sole traders earn different amounts throughout the year. This can be common where work depends on transport contracts, construction projects, seasonal demand, agricultural cycles or customer requirements.

The lender may look beyond a single month's income to understand the business's wider financial position. The documents required will depend on the lender and transaction.

TAFS can help present relevant income information as part of the application.

Does personal income count?

A lender assessing a sole trader may consider acceptable personal and business income information as part of its affordability assessment.

The treatment of different income sources varies between lenders. The lender may also consider personal financial commitments.

TAFS can review the information available and determine which lenders may be appropriate.

Credit, documents and deposits

Does a personal home loan affect trailer finance?

A home loan does not automatically prevent a sole trader from obtaining commercial trailer finance. However, mortgage repayments can form part of the lender's assessment of existing financial commitments.

Other debts may also be considered, including vehicle finance, equipment loans, personal loans, credit cards and other commercial finance.

The lender will assess the applicant's overall ability to meet the proposed repayments.

Does personal credit history matter?

Yes. A sole trader's personal credit history can form an important part of the commercial finance assessment.

Lenders may consider current credit accounts, repayment history, defaults, existing finance and other relevant credit information.

A satisfactory credit history may support an application. Where credit issues exist, lender selection can become more important.

Can a sole trader get low doc trailer finance?

Potentially. Some established sole traders may qualify for commercial trailer finance with reduced financial documentation.

Eligibility can depend on ABN history, GST registration, credit profile, existing finance, trailer purchase price, asset age and lender requirements.

Low doc finance does not mean no financial assessment is completed.

Do sole traders need financial statements?

Not every commercial lender requires the same financial documents.

Depending on the applicant and finance product, the lender may request personal tax returns, business financial statements, BAS, business bank statements or other income evidence. Some eligible applications may be assessed using reduced documentation.

TAFS can explain which documents are needed after reviewing your business.

Can a sole trader finance a trailer without a deposit?

Potentially. Some sole traders may qualify for full purchase-price finance. Other applications may require or benefit from a deposit.

The lender can consider trading history, credit profile, existing commitments, trailer age, purchase price and overall financial position.

TAFS can review the transaction and explain the deposit requirements of suitable lenders.

Can a trade-in help?

A sole trader replacing an existing trailer may be able to use the trade-in value towards the purchase. Where finance remains on the existing asset, the outstanding payout needs to be considered.

TAFS can review the existing trailer payout, trade-in value, new purchase price, proposed finance amount and current commitments.

The final structure will depend on the lender and transaction.

Where you're buying the trailer

Buying a trailer through a dealership

Sole traders can apply for commercial finance when purchasing trailers through dealers. Dealer purchases generally involve established purchase documentation.

The lender may require the dealer invoice, trailer details, manufacturer, build year, purchase price and identification information.

TAFS can coordinate the finance process through settlement with the dealer.

Private sale trailer finance for sole traders

A sole trader may purchase a trailer directly from another transport operator or business.

Private-sale transactions can require additional information around seller identity, ownership, VIN or chassis details, existing finance, PPSR information, the purchase agreement and settlement instructions.

TAFS can review the private sale and help coordinate the relevant lender requirements.

Auction trailer finance for sole traders

Commercial auctions can provide access to used trailers across a range of ages and configurations. Sole traders may be able to finance eligible auction purchases.

However, auction transactions can involve strict payment deadlines, buyer's premiums, limited inspection information, additional asset checks and final lender approval after bidding.

If you're planning to bid, discuss your finance position with TAFS beforehand.

Sole trader finance by trailer type

Sole trader finance for semi trailers

Owner-drivers and transport operators may purchase semi trailers for general freight, linehaul or specialised transport.

The lender may assess the asset alongside the sole trader's existing prime mover and finance commitments.

Sole trader finance for flat top and drop deck trailers

Flat tops and drop decks are commonly used to transport commercial freight, machinery and materials.

The lender can consider the trailer's configuration, age, value and intended work.

Sole trader finance for low loaders

Civil contractors and machinery operators may purchase low loaders to transport heavy equipment.

These can be specialised assets, with lenders considering the trailer configuration, axle setup, rated capacities, purchase price and remaining working life.

Sole trader finance for tipper and side tipper trailers

Sole traders operating in civil construction, quarrying or bulk haulage may require tipping trailers.

The lender may consider body condition, hydraulic systems, trailer age, axle configuration and intended use.

Sole trader finance for dog trailers

An owner-driver with an existing tipper truck may purchase a dog trailer to increase carrying capacity.

The lender can assess the trailer alongside the towing vehicle, existing finance and overall business position.

Sole trader finance for refrigerated trailers

Transport operators may purchase refrigerated trailers for temperature-controlled freight.

The lender can consider both the trailer and the refrigeration unit. Age, condition and purchase value may affect the available options.

Sole trader finance for tanker trailers

Sole traders operating specialised liquid transport businesses may require tanker trailers.

The lender may assess the tank specification, capacity, previous use, condition, ancillary equipment and purchase price.

New trailer finance for sole traders

A sole trader may purchase a brand-new commercial trailer through a manufacturer or dealership. New trailers generally provide clear information about the manufacturer, build year, trailer specification, purchase price and expected working life.

Some new trailers may involve custom builds, deposits and progress payments. The lender can assess the completed asset and the sole trader's overall financial position.

Used trailer finance for sole traders

Purchasing a second-hand trailer can be a practical option for sole traders looking to manage the initial purchase cost.

Lenders may consider trailer age, condition, manufacturer, purchase price, expected remaining working life and age at the end of the proposed finance term. Older trailers may have fewer suitable lenders.

TAFS can review the individual asset before recommending a finance structure.

Trucks, business structure and growth

Financing a trailer separately from the truck

You don't need to purchase a truck and trailer together. If you already own or finance a suitable prime mover, the trailer may potentially be financed as a separate commercial asset.

The lender may still consider existing truck repayments when assessing affordability. For a sole trader, this can include reviewing how current vehicle commitments fit alongside business income and personal financial obligations.

TAFS can assess the trailer purchase within your overall financial position.

Financing a prime mover and trailer together

A sole trader may need to purchase both a prime mover and trailer to establish or expand their operation.

The lender can consider the combined purchase amount, the age and value of each asset, transport experience, existing work, business income, personal financial commitments, credit history and available deposit.

The assets may be financed together or through separate facilities depending on lender requirements.

What if you're changing from sole trader to a company?

Some business owners operate as sole traders before establishing a company. If you're changing business structure, the lender may need to understand your previous trading history, the new business entity, existing finance, continuity of operations and the proposed borrower.

A company is a separate legal entity, so existing sole trader trading history may need to be supported with additional information.

TAFS can review the circumstances before recommending a finance application.

What if you're financing another trailer?

An established sole trader may already have several trucks, trailers or other assets under finance.

An additional trailer can support new contracts, higher freight volumes, fleet replacement, different types of work and business growth. The lender may assess the new repayment alongside existing commitments.

TAFS can review the wider financial position before determining the most suitable approach.

What documents are required for Sole Trader Trailer Finance?

The exact requirements depend on the lender, applicant and trailer.

Not every application requires every document.

TAFS can advise which information is relevant once the business and transaction have been reviewed.

Documents may include:

  • Personal identification
  • ABN information
  • GST registration details
  • Personal tax returns
  • Business financial statements
  • BAS
  • Business bank statements
  • Details of existing finance
  • Trailer quote or invoice
  • Manufacturer and model
  • Build year
  • VIN or chassis number
  • Deposit or trade-in information

What lenders look at for Sole Trader Trailer Finance

There isn't one checklist every lender uses. Depending on the application, the following factors may matter.

ABN and trading history

The length of time the sole trader has been operating may influence lender eligibility.

Industry experience

Experience in transport, civil construction, agriculture or another relevant industry can help establish the business purpose of the purchase.

Business income

Lenders may assess revenue, expenses, cash flow and available financial documentation.

Personal financial position

Personal debts and commitments can form part of the assessment.

Credit profile

Personal credit history may influence the available options.

Existing asset finance

Truck, trailer and machinery repayments can affect affordability.

Trailer age and condition

The trailer must meet lender requirements, including relevant asset-age and valuation policies.

Deposit or trade-in

A contribution may strengthen some applications, although it is not always required.

Example scenario

How TAFS approaches sole trader trailer finance

An owner-driver operating as a sole trader may need to purchase a commercial trailer to take on additional freight work or reduce their reliance on hired equipment.

Unlike a company, a sole trader operates the business as an individual, meaning lenders generally assess both the applicant's business income and personal financial commitments.

TAFS can review the operator's ABN history, transport experience, current income, existing truck finance and the trailer being purchased.

The trailer's age, purchase value and intended commercial use also influence which lenders may be suitable.

By reviewing the complete financial position, TAFS can identify commercial finance options that suit the individual and their business.

Situations like this demonstrate why sole trader trailer finance requires more than assessing the asset alone. The right lender needs to be comfortable with the operator, their existing commitments and the work the trailer will support.

  • Sole trader owner-driver
  • Commercial trailer finance
  • Transport business
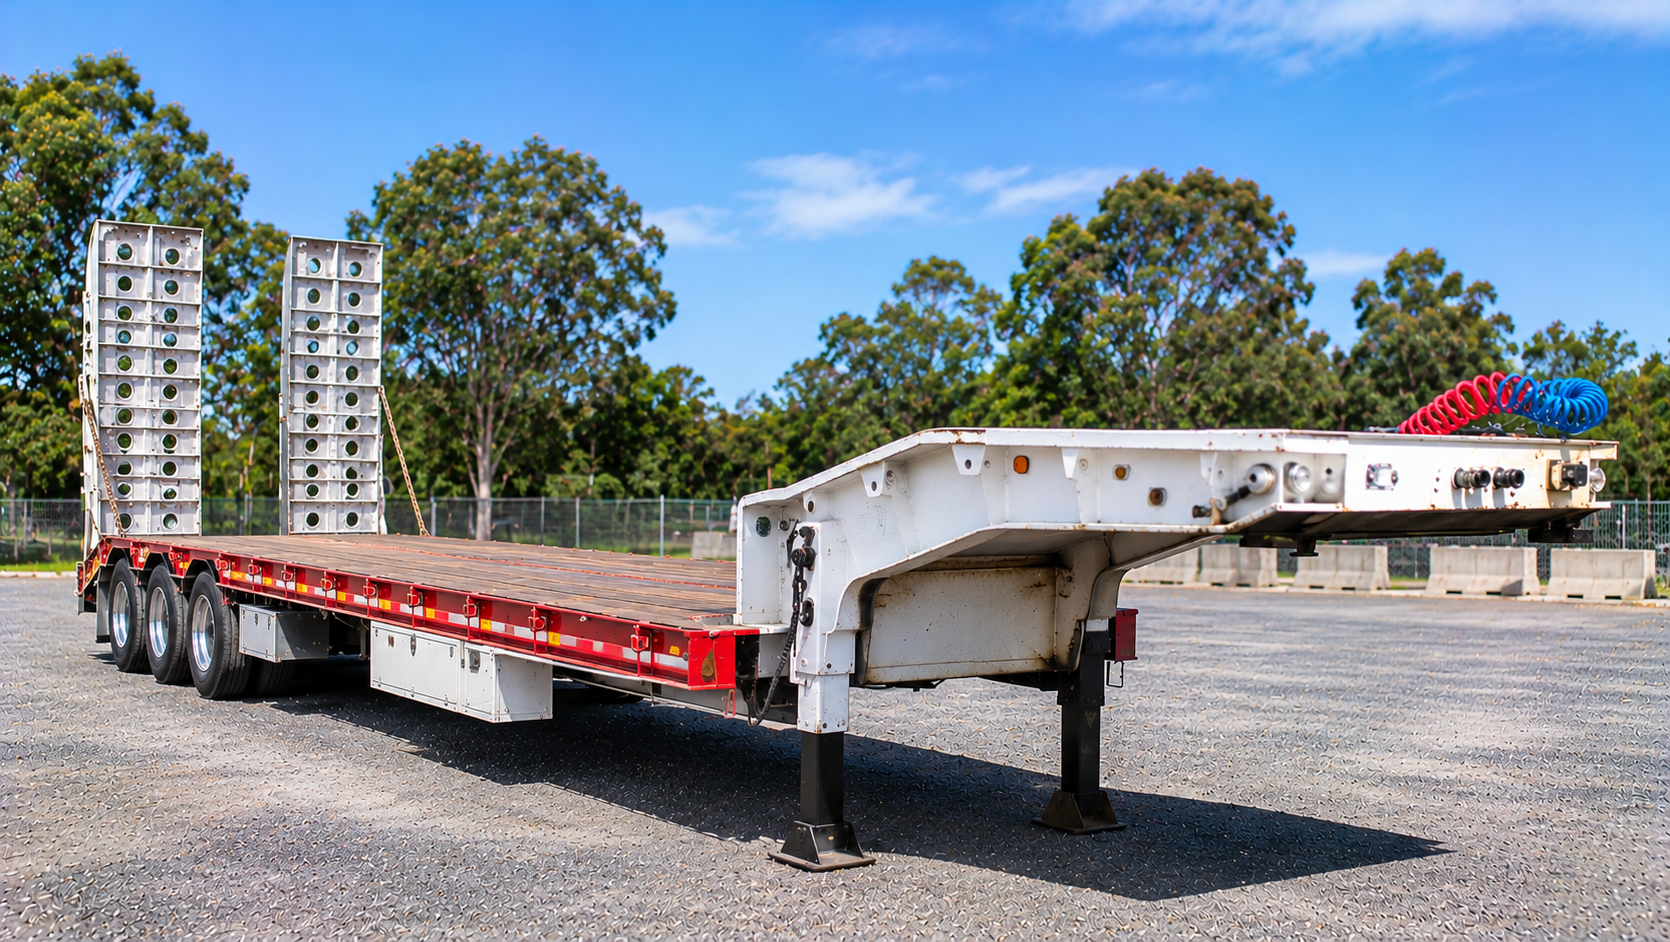
Industrial lowboy trailer in a depot yard
Why TAFS

Why sole traders use TAFS for trailer finance

80+ Lenders

We have access to a broad panel of banks and non-bank commercial lenders with different approaches to sole trader applications, business history and asset finance.

Internal credit team

Our team reviews the applicant's business, personal financial position and proposed trailer before approaching lenders.

Commercial asset finance experience

We work with Australian owner-drivers, contractors and businesses purchasing trucks, trailers, machinery and other commercial equipment.

Specialised asset finance brokers

Sole trader finance can involve assessing business income and personal financial commitments together. TAFS reviews the complete application to identify suitable lenders and structure the finance around the business.

Trusted lender partners:

Azora Banjo Bizcap Branded Financial Capify CFI Finance Dynamoney Finance One Grenke Judo Bank Lumi MoneyMe
The TAFS Process

How Sole Trader Trailer Finance works with TAFS

  • Step 1

    Tell us about your business

    Share your ABN details, trading history, industry experience and the trailer you're planning to purchase.

  • Step 2

    We review the application

    Our team considers the business, income, personal financial commitments, credit profile and asset.

  • Step 3

    We compare suitable lenders

    We assess the application across our lender panel and identify finance options suited to the sole trader and proposed purchase.

  • Step 4

    We manage approval and settlement

    Once you've selected an option, we coordinate the lender requirements, documentation and settlement.

FAQ

Sole Trader Trailer Finance FAQs

We don't just send applications out. We structure them properly from the start.

  • Can a sole trader get trailer finance?

    Yes. Sole traders can apply for commercial trailer finance, subject to lender requirements and the overall application.

  • Do I need to register a company to finance a trailer?

    No. You don't necessarily need a company to obtain commercial trailer finance. Eligible sole traders can apply in their own legal capacity.

  • Do I need an ABN for sole trader trailer finance?

    An ABN is generally required for commercial trailer finance applications. The lender may also consider how long the business has been operating.

  • How long do I need to be a sole trader before applying?

    There is no single minimum trading-history requirement across every lender. Some lenders may consider shorter trading histories where the wider application meets their criteria.

  • Can I get trailer finance with a new sole trader ABN?

    Potentially. Industry experience, income, credit profile, deposit and trailer details can influence available options.

    New ABN Trailer Finance →
  • Do sole traders need to be GST registered?

    Not every lender has the same GST registration requirements. Some consider GST registration as part of their eligibility criteria.

  • Does my personal credit score matter?

    Personal credit history can form part of the assessment because a sole trader operates the business as an individual.

  • Does my home loan affect trailer finance?

    A home loan doesn't automatically prevent approval. However, mortgage repayments may be considered alongside other financial commitments.

  • Can I use business income to qualify for trailer finance?

    Yes. Lenders may assess business income, expenses and cash flow when determining affordability.

  • Do I need financial statements?

    Not in every case. Documentation requirements vary between lenders, and reduced-documentation options may be available to eligible applicants.

  • Can sole traders get low doc trailer finance?

    Potentially. Eligibility depends on the lender, ABN history, credit profile, trailer and overall application.

    Low Doc Trailer Finance →
  • Can I get trailer finance without a deposit?

    Potentially. Some applications may qualify for full purchase-price finance, while others may require or benefit from a deposit.

  • Can I finance a used trailer as a sole trader?

    Yes, potentially. The lender will consider the trailer's age, condition, value and the overall application.

    Used Trailer Finance →
  • Can I finance a new trailer as a sole trader?

    Yes, potentially. Eligible sole traders may finance new commercial trailers purchased through dealers and manufacturers.

    New Trailer Finance →
  • Can I finance a trailer bought privately?

    Potentially. Private-sale transactions may require additional seller, ownership and asset checks.

    Private Sale Trailer Finance →
  • Can I finance a trailer purchased at auction?

    Potentially. Speak with TAFS before bidding so your likely finance position can be reviewed.

    Auction Trailer Finance →
  • Can I finance a trailer without buying a truck?

    Yes. The trailer may be financed separately where the business has a suitable operating arrangement and meets lender requirements.

  • Can I finance a prime mover and trailer together?

    Potentially. The lender may assess both assets and the combined finance requirement.

    Prime Mover Finance →
  • Can I finance more than one trailer as a sole trader?

    Yes, potentially. The lender will consider the total finance requirement, business income and existing commitments.

  • Can a sole trader get trailer finance with bad credit?

    Potentially. The lender will consider the type of credit issue, current financial position and trailer being purchased.

    Bad Credit Trailer Finance →
  • How long can a sole trader finance a trailer for?

    Finance terms depend on the lender, applicant and trailer. Asset age and expected remaining working life may influence the available term.

  • How quickly can Sole Trader Trailer Finance be approved?

    Straightforward applications may progress quickly once the required information is available. Applications requiring additional income verification or asset checks may take longer.

Ready to finance your next trailer as a sole trader?

Tell us about your business, the trailer you're buying and where you're at with your current finance commitments.

We'll review your application and compare suitable trailer finance options across our lender panel.