Trusted by 3000+ clients

Rigid Truck Finance

Finance the chassis, the body and the work it has to do.

Light, medium or heavy rigid, we'll structure the finance around the truck you're buying and the licence class your drivers hold.

With more than 80 lenders on our panel, we can line up options whether you're buying a complete truck off a dealer floor or a bare chassis that still needs a body built on it.

Rigid Truck Finance

Rigid truck finance for Australian businesses

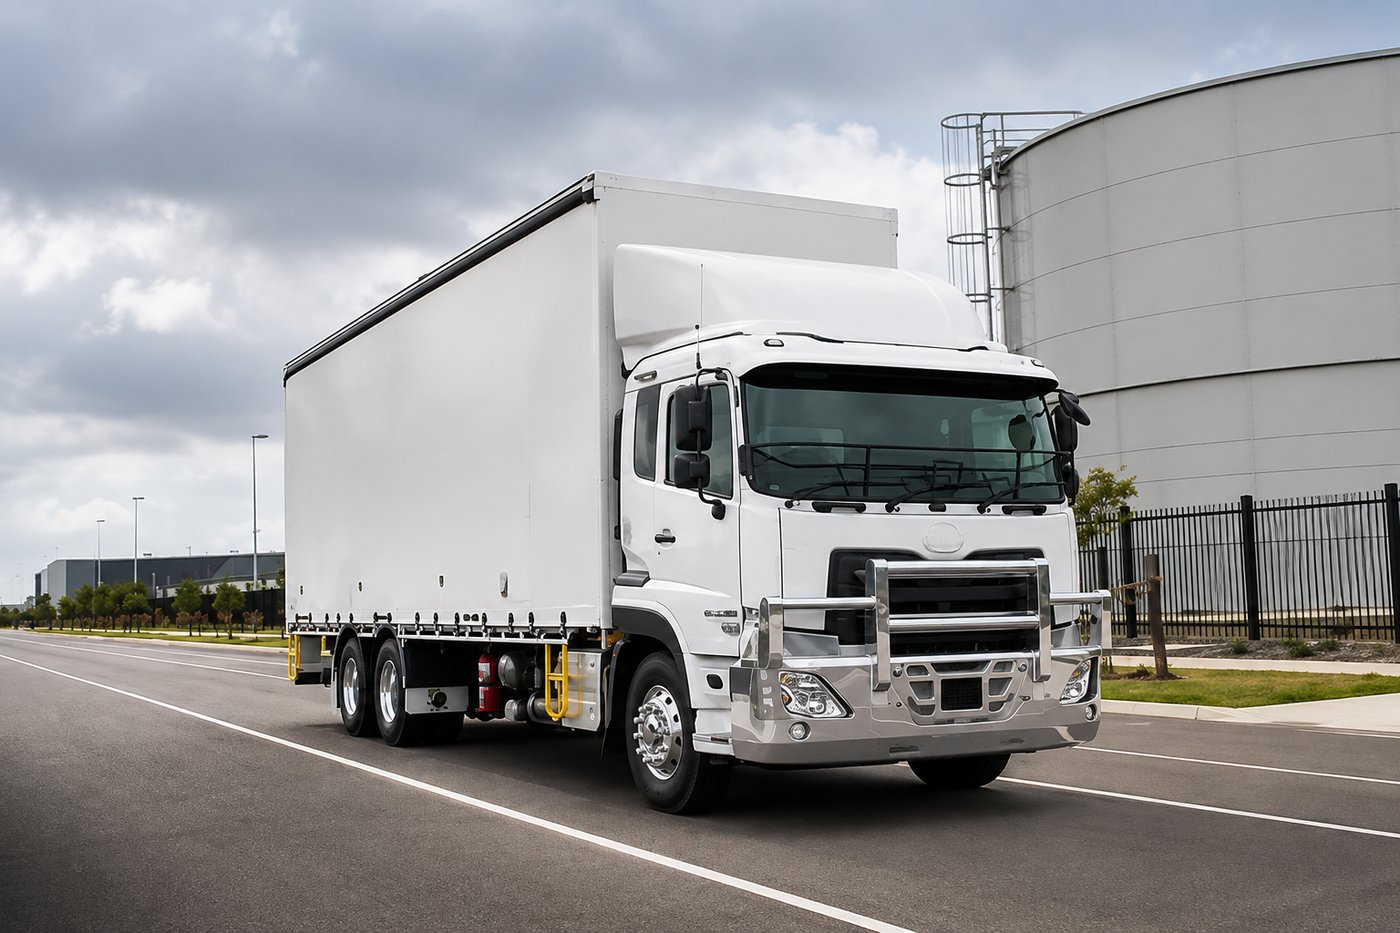
A rigid truck carries its body on a single fixed chassis, with no turntable and no separate trailer. That one structural difference shapes the whole finance conversation.

Rigids sit across a wide band. A light rigid pantech doing suburban parcel runs and a heavy rigid tipper on a council contract are both rigid trucks, but they are different assets to a lender, at different price points, with different working lives.

Most rigid purchases fall between roughly $40,000 and $250,000, which puts them inside the appetite of mainstream commercial lenders as well as the specialist truck financiers. That usually means more options than a prime mover deal, not fewer.

TAFS works through the chassis, the body, the GVM class and the work the truck is going into before approaching lenders, so the application lands with the ones whose asset policy actually fits. See the full range of truck finance options.

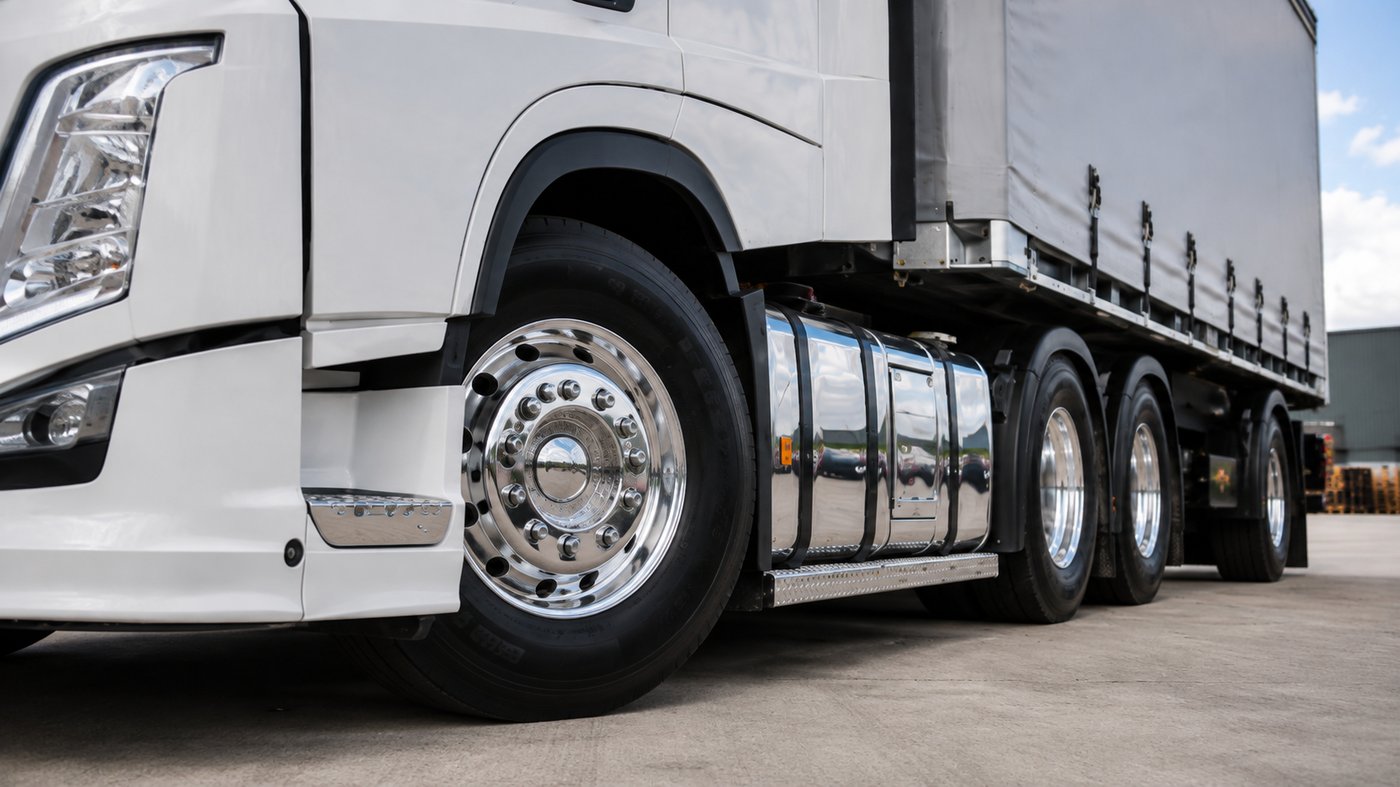
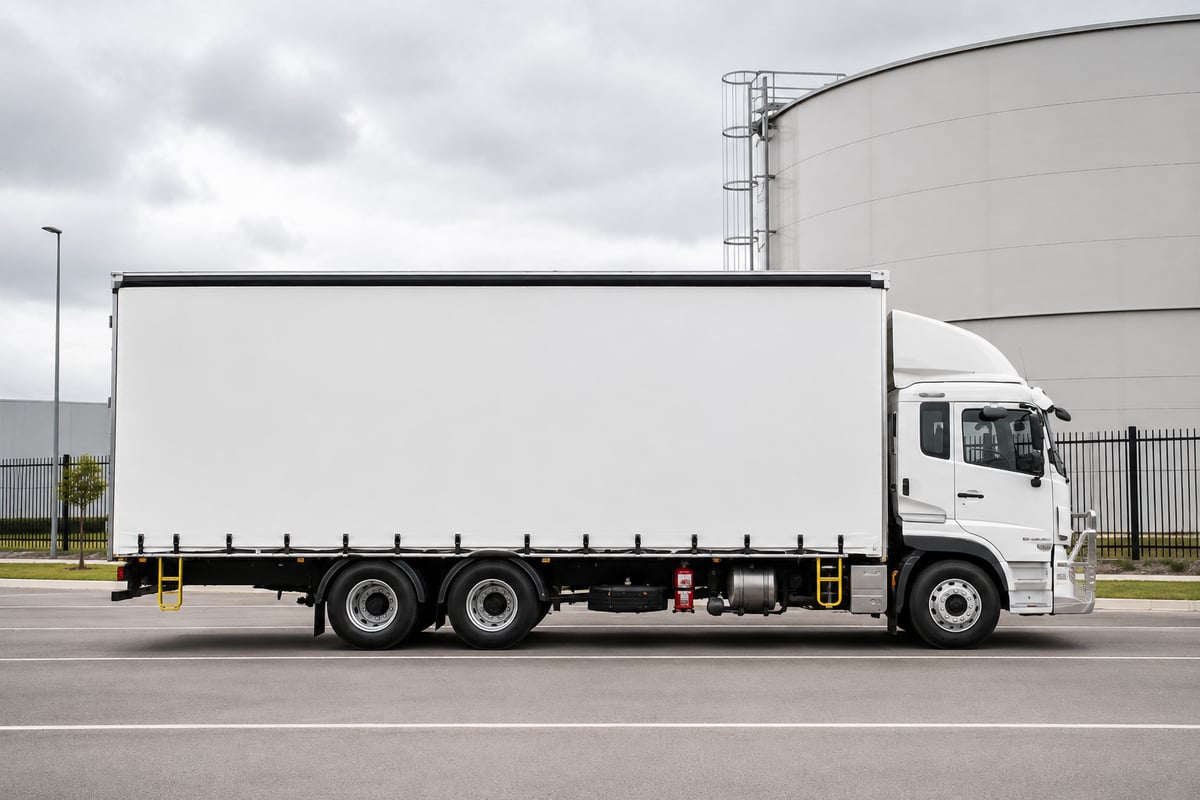
Rigid truck side profile

Financing a rigid isn't the same as financing a prime mover

Operators moving between the two are often surprised that the finance works differently. The asset is doing a different job, and lenders read it that way.

The body is part of the deal. A prime mover is a complete unit. A rigid frequently arrives as a chassis that a body builder then fits out. Lenders need to know the total delivered value, who is building the body, and when it will be finished, because funds usually cannot settle until the truck is complete and roadworthy.

GVM class changes the product. Under 4.5 tonnes, some lenders will write the deal as a light commercial vehicle rather than a truck, which can open up different terms. Above that, it is assessed as commercial truck finance and the licence class your drivers hold can come into the conversation.

The duty cycle is harsher on paper. Metro distribution means constant stop-start work, high engine hours against relatively low kilometres. Lenders assessing a used rigid look at hours and service history as much as the odometer.

Values are lower and appetite is broader. A smaller amount financed brings more lenders into play, and often reduces the pressure for a deposit compared with a high-value prime mover purchase.

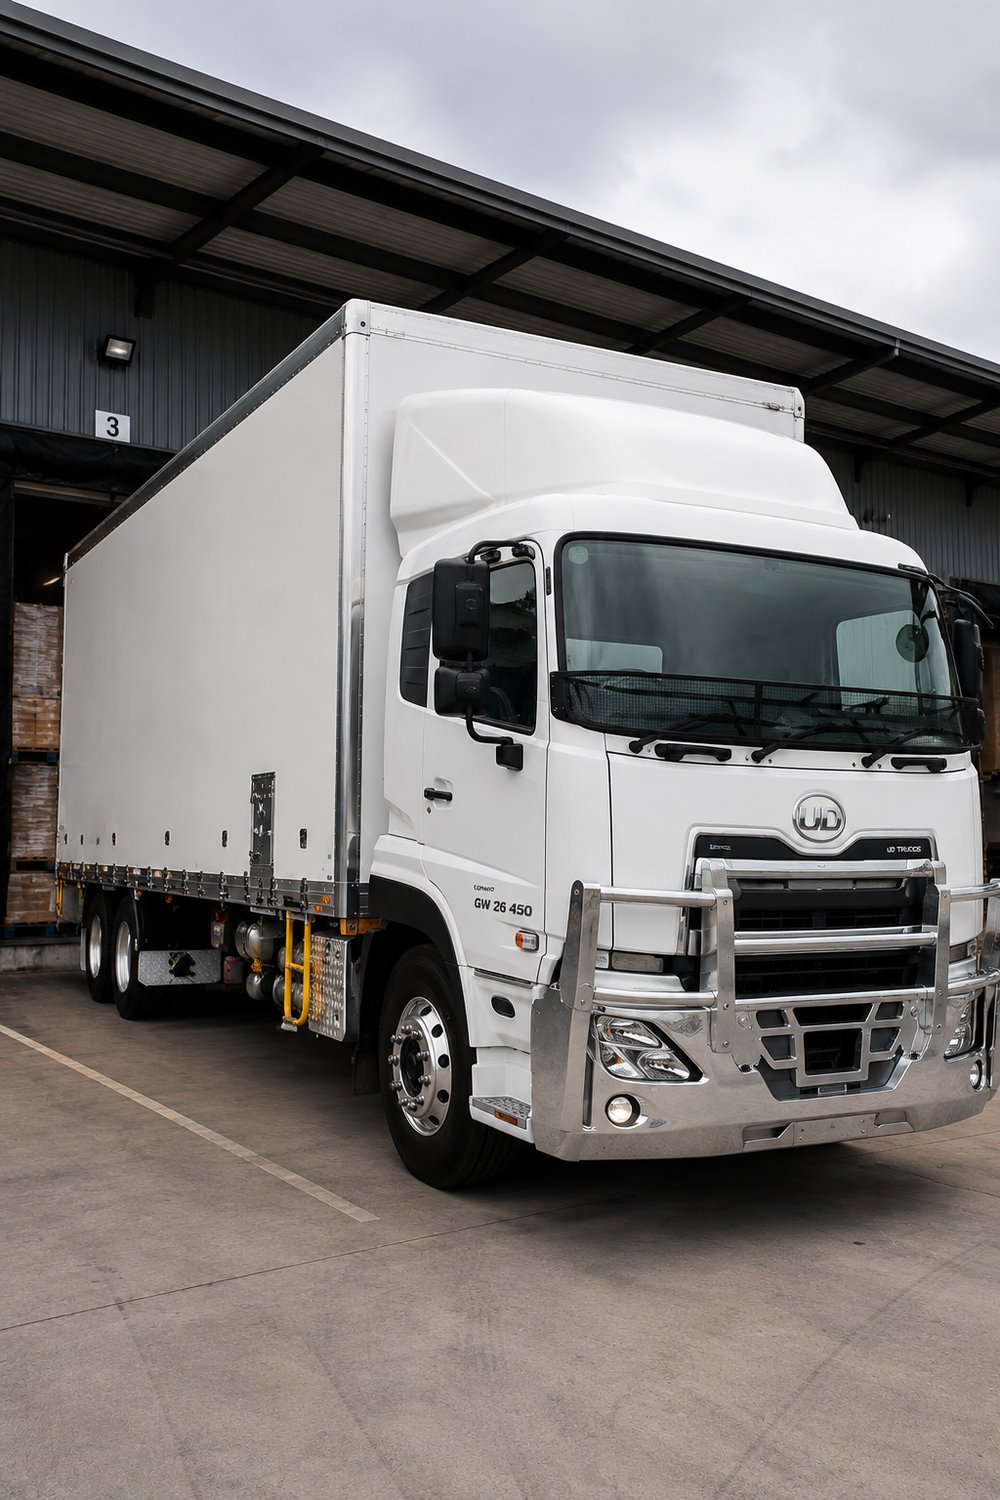
Close-up of a rigid truck

What rigid trucks can be financed?

TAFS can arrange finance across the full rigid range, by GVM class and by body type. This can include:

  • Light rigid trucks (4.5–8t GVM)
  • Medium rigid trucks (8–15t GVM)
  • Heavy rigid trucks (15t+ GVM)
  • Pantech and box body trucks
  • Curtainsider and tautliner bodies
  • Tray and flat top bodies
  • Tipper bodies on rigid chassis
  • Refrigerated and insulated bodies
  • Ex-fleet and ex-lease rigids
  • Service and tradesman body trucks
  • Bare chassis awaiting a body build
  • Crane and vehicle-mounted loader trucks

We can also help when the chassis and the body are being bought from two different suppliers.

  • 15,000+Assets Financed And Businesses Helped
  • $350M+Total Business Funding
  • 80+Lenders To Compare
  • 30+Years Of Business Experience
  • 93%Client Success Rate

Stepping up from a ute or van?

A rigid truck is the usual next step when a van has run out of payload and you're turning work away or splitting it across two trips.

The finance is a different conversation from a vehicle loan. You're moving into commercial truck lending, where the asset is assessed on its own merits alongside the business.

Sitting just under 4.5 tonnes GVM can keep the deal inside light commercial territory with some lenders. Going above it changes both the finance product and the licence your drivers need, so it's worth deciding deliberately rather than by accident.

We'll talk through where that line sits for the work you're doing before you commit to a truck.
Buying a chassis and building a body?

Buying a cab chassis from a dealer and having a body builder fit it out gives you exactly the truck you want. It also splits the purchase across two suppliers and two invoices.

Lenders can fund the complete delivered cost, but they need the full picture up front: chassis price, body quote, who is building it and how long it will take.

Settlement timing is the part that catches people out. Funds generally cannot be released until the truck is finished, registered and roadworthy, which can be weeks after the chassis is ready.

We structure these so the chassis supplier and the body builder both get paid at the right point, without you bridging the gap yourself.

New and used rigid truck finance

TAFS can arrange finance for new rigids, used rigids and ex-fleet trucks coming out of major logistics operators.

A new rigid comes with clear supplier documentation, full warranty and a body built to your specification, which makes it straightforward for a lender to value.

The used rigid market has a genuine advantage the prime mover market doesn't share as strongly. Large distribution fleets cycle their trucks on fixed replacement schedules, so well-maintained ex-fleet and ex-lease rigids with complete service history come onto the market regularly.

Engine hours matter more than kilometres on a used rigid. A metro truck can show modest kilometres and heavy hours from years of stop-start work, and lenders assessing the asset will look at both.

Lenders can consider:

  • GVM class
  • Vehicle age
  • Engine hours and kilometres
  • Body type and condition
  • Service history
  • Total delivered price
  • Whether the body is retained, replaced or newly built

Dealer, body builder and private sale purchases

Rigid purchases involve more supplier combinations than most truck deals. Where the truck comes from changes how the finance settles.

Complete truck from a dealer

A body-on, ready-to-drive rigid off a dealer floor is the simplest deal to fund. One invoice, one supplier, one settlement.

Stock trucks with a common body type can often move from approval to settlement quickly.

Chassis plus body builder

Two suppliers, two invoices and a build period in between. Lenders will want the chassis price, the body quote and an expected completion date before approval.

Settlement usually waits until the truck is complete and registered, so the build timeline becomes part of the finance timeline.

Private sale and ex-fleet

Trucks bought directly from another business, or released from a large fleet's replacement cycle, can both be financed.

The lender can require additional checks on the seller, ownership and the truck itself before settlement.

What lenders look at

Rigid applications turn on a slightly different set of factors from other truck finance. Depending on the deal, lenders will generally weigh a combination of the following.

GVM class

Where the truck sits across light, medium and heavy rigid determines which lender product applies and, in some cases, whether it is written as truck or light commercial finance.

The body and who built it

Body type, age, condition and the builder's reputation feed into the truck's resale value, which is what the lender is securing against.

Your business

Trading history, turnover, cash flow and existing commitments all shape what is available. Contracted or recurring delivery work strengthens an application.

Duty cycle and hours

Metro stop-start work accumulates engine hours faster than the odometer suggests. On a used rigid, hours and service history can matter more than kilometres.

Licensing and drivers

Medium and heavy rigids need MR or HR licensed drivers. Some lenders ask how the truck will be staffed, particularly for a first truck purchase.

Deposit or trade-in

Lower purchase prices mean deposits are required less often than on high-value trucks. Trading the van or truck being replaced can still strengthen the application.

Recent TAFS deal

A recent TAFS rigid truck deal

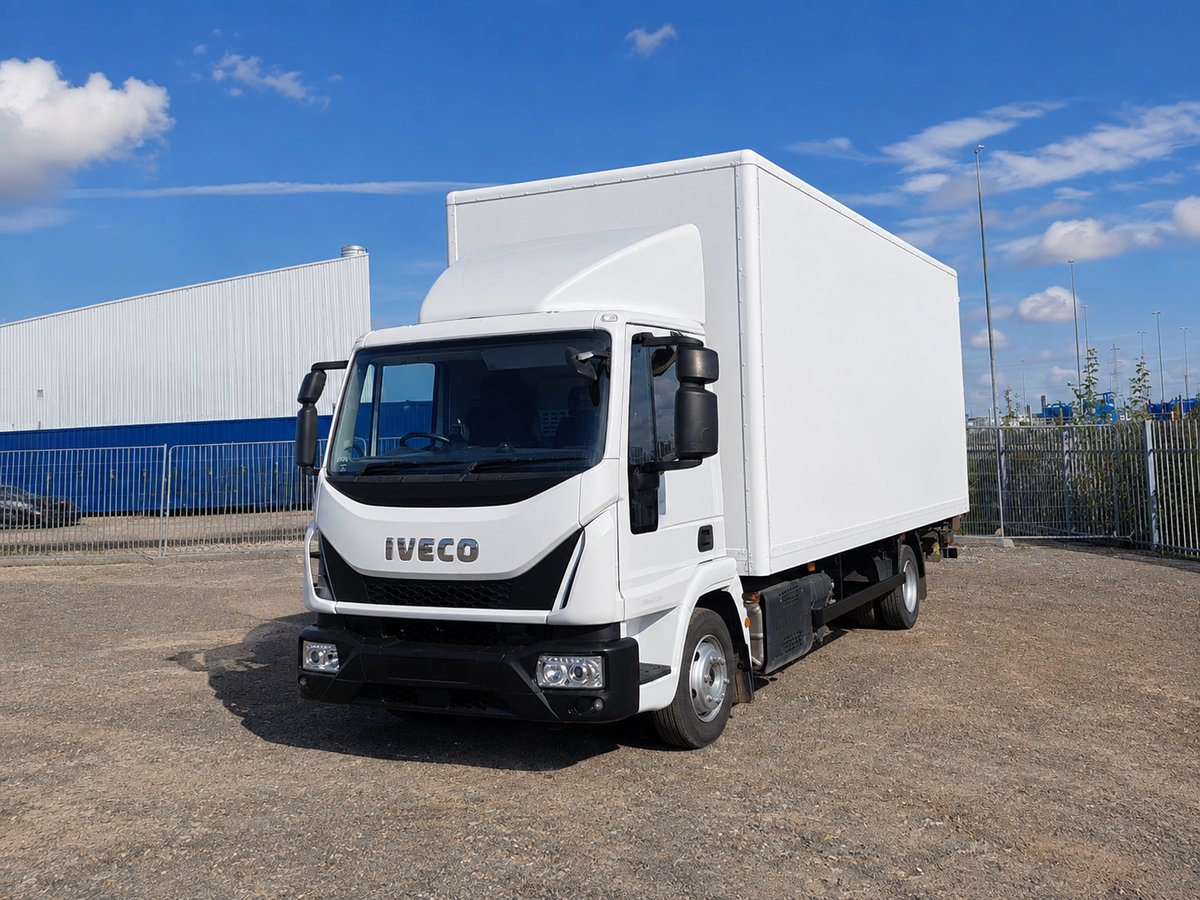
One recent TAFS client, a Queensland logistics operator, was purchasing a 2018 Iveco rigid truck through a private sale.

The truck was an older asset and the vendor had other buyers waiting, so lender selection and speed both mattered. The deal needed a lender comfortable with the age of the truck and the private-sale transaction, and one that could move quickly enough to settle before the vendor walked.

TAFS arranged the purchase using a 48-month chattel mortgage with no balloon, and the deal settled within a month of the enquiry. The client added the truck to the fleet and will own it outright at the end of the term.

Deals like this are a good example of why rigid truck finance often comes down to lender fit. A private-sale truck that sits outside one lender's policy, or moves too slowly through another, can settle in weeks with the right one.

  • 2018 Iveco rigid truck
  • Private sale
  • 48-month chattel mortgage, no balloon
2018 Iveco rigid truck financed by TAFS
Why TAFS

Why businesses use TAFS for rigid truck finance

80+ Lenders

We have access to a broad panel of banks and specialist commercial lenders, giving us more ways to structure a deal.

Internal credit team

Applications are reviewed before they're submitted so the lender gets a clear picture of the business, the truck and the purpose of the finance.

93% Client success rate

We focus on matching each application with lenders suited to the deal and presenting the application properly from the start.

Commercial asset finance specialists

Our team works with businesses purchasing trucks, trailers, machinery and equipment every day. We understand how commercial assets are assessed and how finance needs to fit around the operation of the business.

Trusted lender partners:

Azora Banjo Bizcap Branded Financial Capify CFI Finance Dynamoney Finance One Grenke Judo Bank Lumi MoneyMe
The TAFS Process

How rigid truck finance works with TAFS

  • Step 1

    Tell us about the truck

    Send us the chassis details, the body quote if there is one, the GVM and some information about your business.

  • Step 2

    We review the application

    Our team looks at the asset, business profile, finance requirements and anything else that will influence lender selection.

  • Step 3

    We find suitable options

    We compare the application against lenders from our panel and identify the options suited to the transaction.

  • Step 4

    We manage approval and settlement

    Once you've chosen an option, we work through the lender requirements, the body build timeline and documentation to get the truck settled.

FAQ

Rigid Truck Finance FAQs

We don't just send applications out. We structure them properly from the start.

  • What counts as a rigid truck?

    A rigid truck carries its body on one fixed chassis, with no turntable and no separate trailer. They are generally grouped as light rigid (4.5 to 8 tonnes GVM), medium rigid (8 to 15 tonnes) and heavy rigid (above 15 tonnes). A prime mover, which tows a trailer through a fifth wheel, is not a rigid.

  • Can I finance the chassis and the body together?

    Yes. Lenders can fund the complete delivered cost of the truck even when the chassis and the body come from different suppliers. They will want the chassis price, the body builder's quote and an expected completion date up front, because settlement generally waits until the truck is finished, registered and roadworthy.

  • Do I need an MR or HR licence to finance a rigid truck?

    Holding the licence yourself is not a finance requirement, but the truck does need to be legally driveable by someone in the business. Medium rigids generally require an MR licence and heavy rigids an HR licence. Some lenders will ask how the truck is going to be staffed, particularly on a first truck purchase.

  • Can I finance a rigid truck under 4.5 tonnes GVM?

    Yes, and it is worth flagging early. Below 4.5 tonnes GVM some lenders will write the deal as light commercial vehicle finance rather than truck finance, which can change the terms available. It also means a car licence is generally sufficient to drive it.

  • Can I finance an ex-fleet or ex-lease rigid truck?

    Yes. Large distribution fleets replace rigids on fixed schedules, so these trucks come to market regularly and often carry complete service history, which lenders view positively. The truck still needs to sit inside the lender's age and condition policy.

  • Can I finance a used rigid truck?

    Yes, across a wide range of ages and price points. On a used rigid, lenders look closely at engine hours alongside kilometres. Years of metro stop-start work can put significant hours on a truck that still shows modest distance travelled.

  • Can I finance a tipper body on a rigid chassis?

    Yes. A tipper body fitted to a rigid chassis is financed as one asset. The body's construction and capacity feed into how the lender values the completed truck.

    Tipper Truck Finance →
  • Do I need a deposit?

    Often not. Rigid purchase prices generally sit well below prime mover territory, which brings more lenders into play and reduces the pressure for a deposit. Contributing cash or trading in the vehicle being replaced can still improve the options available.

  • Can I finance a rigid truck with a new ABN?

    Yes. Finance can be available for newer businesses. Previous industry experience, credit history, the work available and the truck being purchased all carry more weight where trading history is limited.

    New ABN Truck Finance →
  • Can a sole trader finance a rigid truck?

    Yes. Sole traders can apply where the truck is being purchased predominantly for business use and the application meets lender criteria.

    Sole Trader Truck Finance →
  • How long can I finance a rigid truck for?

    Terms vary with the truck and the applicant. Rigids are often held longer than prime movers, so the expected age and condition of the truck at the end of the term becomes an important part of the lender's assessment.

  • How quickly can rigid truck finance be approved?

    Approval on a straightforward deal can move quickly once the information is available. Settlement is the part worth planning around: a complete truck off a dealer floor can settle fast, while a chassis going to a body builder settles when the build finishes.

Ready to finance your next rigid truck?

Tell us what you're buying - a complete truck off the floor, or a chassis with a body still to come.

We'll review the truck, the build timeline if there is one, and compare suitable finance options across our lender panel.