Trusted by 3000+ clients

New Truck Finance

Finance your next new truck with a team that understands commercial vehicles.

Buying your first new truck, replacing an ageing vehicle or adding another one to the fleet, we'll structure the finance around your business and the truck you're purchasing.

TAFS works with businesses across transport, logistics, construction, civil, trades and distribution, with access to more than 80 lenders for new commercial truck finance.

New Truck Finance

New truck finance for Australian businesses

New truck finance is commercial asset finance used to purchase brand-new trucks for business purposes.

It can be used for vehicles purchased through truck dealerships, manufacturers and authorised suppliers across Australia.

Finance can cover a wide range of new commercial vehicles, from light trucks and rigid trucks through to prime movers and specialised vehicles.

The options available will depend on your business, the truck you're buying, the purchase price, any body or equipment being fitted and the strength of the overall application.

TAFS reviews these factors before approaching lenders so the finance can be matched with the truck and the business. See the full range of truck finance options.

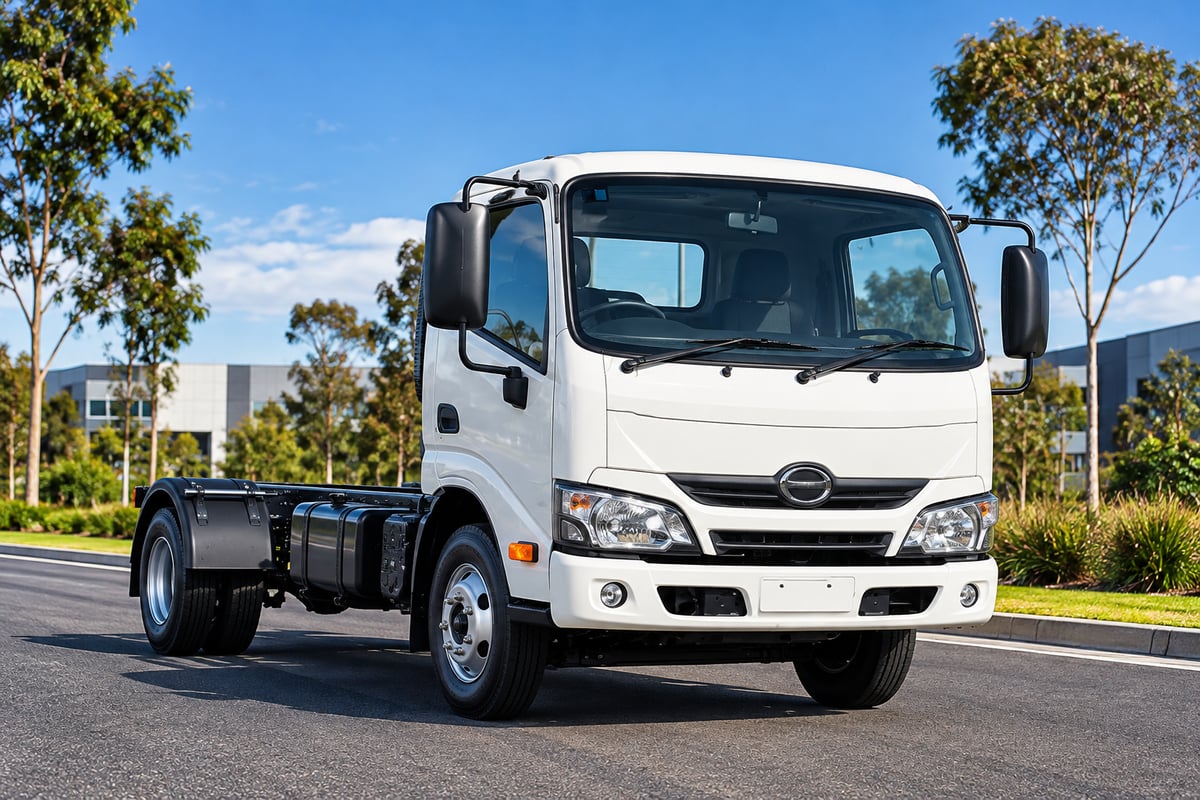
White cab chassis truck on an industrial road

Financing a new truck is about more than the purchase price

A new truck may be straightforward from an asset perspective, but the finance still needs to fit the business.

A transport business replacing a high-kilometre truck presents differently from a new operator purchasing their first vehicle.

Likewise, a business adding a truck for a new contract has a different story from one simply upgrading an existing asset.

Our team reviews the commercial reason behind the purchase before the application is submitted.

Lenders can consider:

  • How long the business has been trading
  • Turnover and cash flow
  • Existing vehicle and equipment finance
  • Industry experience
  • The purchase price
  • Whether the truck replaces an existing vehicle
  • Whether it adds new capacity
  • Any deposit or trade-in
  • The body or fit-out being added
  • The expected use of the vehicle

What new trucks can be financed?

TAFS can arrange finance across a broad range of new commercial trucks. This can include:

  • Prime movers
  • Rigid trucks
  • Light trucks
  • Tipper trucks
  • Crane trucks
  • Refrigerated trucks
  • Tanker trucks
  • Tow trucks
  • Delivery trucks
  • Cab chassis trucks
  • Trucks with specialised bodies or commercial fit-outs

We can also help where the truck is being ordered before the final body or equipment has been installed.

  • 15,000+Assets Financed And Businesses Helped
  • $350M+Total Business Funding
  • 80+Lenders To Compare
  • 30+Years Of Business Experience
  • 93%Client Success Rate

Buying your first new truck?

Buying a brand-new truck can be a major step for an owner-operator or growing business. You may be moving from employed driving into your own operation, upgrading from a smaller commercial vehicle or buying your first truck after years of experience in the industry.

Lenders can look at more than the age of the business. Relevant industry experience, credit history, expected work, contracts, purchase price and any contribution towards the truck can all help shape the application.

Growth can also create the need for a vehicle before a business has years of financial history behind it. In those situations lenders may look at current turnover, recent growth, industry experience, existing customer relationships, contracts or work pipeline, current vehicle utilisation and available cash flow.

The fact that the truck is new can also give lenders clearer information about the asset, supplier and expected working life. TAFS can present the wider business position rather than relying only on the age of the ABN.
Adding a new truck to the fleet?

A new truck may also be purchased to create additional capacity.

That can happen when a business takes on new contracts, additional delivery routes, higher freight volumes, new construction projects, additional customers, regional expansion, or work previously handled by subcontractors.

The lender can consider how the new truck fits into the existing operation and whether the additional finance is supported by the business's financial position.

TAFS reviews the current fleet, existing commitments and reason for expansion as part of the application.

Buying more than one at a time?

Businesses can apply to finance multiple new trucks as part of a fleet expansion or replacement program. The lender will assess the combined transaction alongside the business's existing commitments.

Replacing an older truck with a new one

A new truck purchase is often about reliability rather than simply increasing fleet size.

Older vehicles can require more maintenance, create more downtime and become less predictable as kilometres increase.

Where the existing truck still has finance owing, we can review the payout alongside the expected trade-in or sale proceeds.

This helps determine how the replacement transaction can be structured before you commit to the new vehicle.

Replacing an existing truck may help a business:

  • Reduce unplanned downtime
  • Improve vehicle reliability
  • Reduce maintenance pressure
  • Improve fuel efficiency
  • Meet customer or contract requirements
  • Access newer safety and driver-assistance technology
  • Plan fleet replacement more consistently

Dealer purchases, cab chassis and body builds

Most new trucks are purchased through authorised dealers or manufacturers, but not every truck arrives ready for work.

Dealer and manufacturer purchases

Buying through an authorised dealer or manufacturer can help simplify the documentation, because the supplier can provide a formal quote or invoice showing the vehicle details and purchase price.

Depending on the truck, the purchase may involve a factory-built completed vehicle, a cab chassis, a truck with a separately supplied body, dealer-fitted accessories, or specialist equipment installed before delivery.

Where several suppliers are involved, we look at the complete transaction rather than only the base truck.

Cab chassis and body build

Businesses often purchase a cab chassis and then have the working body or equipment built separately. That can include tipper bodies, pantech bodies, refrigerated bodies, crane installations, tanker bodies, tilt trays, service bodies or custom commercial fit-outs.

These purchases can involve several quotes, deposits and completion dates.

Depending on the lender and transaction, the cab chassis and fit-out may be able to form part of the overall finance structure. TAFS can review the full build and determine how it can be presented to suitable lenders.

Factory orders, lead times and deposits

Some new trucks are available immediately. Others may be factory ordered months before delivery.

That can create a different finance process, because the exact settlement date may not be known when the vehicle is first ordered. The dealer may also require an initial deposit well before the final truck is delivered.

How that deposit is treated will depend on the transaction and lender. In some cases it becomes part of your contribution towards the purchase; in others the lender may finance the final balance payable at settlement.

If you're ordering a truck with a longer lead time, speak with TAFS before committing to the purchase — particularly before committing a large deposit where delivery is still several months away.

Before you commit, we can review:

  • Your likely finance position
  • The purchase order
  • Deposit requirements
  • What information needs updating closer to delivery
  • Whether approval terms may need reassessing

Any approval or indicative terms may need to be reassessed if circumstances, lender policies or the final truck details change before settlement.

Trade-ins and existing truck finance

A trade-in can form part of a new truck purchase.

If the truck being traded is owned outright, its value can reduce the amount that needs to be financed.

If finance is still owing, the payout needs to be compared with the trade-in value.

TAFS can review the existing finance alongside the new purchase so you understand the overall position before settlement.

Two ways that can land:

  • If the trade-in value exceeds the payout, the remaining equity may contribute towards the new truck.
  • If the payout exceeds the trade-in value, the shortfall needs to be dealt with as part of the transaction.

Why businesses choose new trucks

A brand-new truck is usually more expensive than a comparable used vehicle, but there can be practical reasons for choosing new. Businesses may prefer a new truck because of:

  • Manufacturer warranty
  • Lower initial kilometres
  • Latest safety technology
  • Greater reliability
  • Newer emissions technology
  • Predictable service history
  • Longer expected working life
  • Ability to order the exact specification required
  • Reduced maintenance uncertainty early on

The right choice depends on the business. For some operators, a good used truck can make more financial sense. For others, reliability, specification and expected utilisation can justify the additional cost of buying new.

A new truck will usually come with manufacturer warranty coverage, though the exact warranty depends on the manufacturer, truck and supplier. Warranty coverage does not change the lender's assessment of whether the finance is affordable, but it can form part of the wider commercial reason for replacing an older truck. Always confirm the warranty terms directly with the dealer or manufacturer before purchase.

What lenders look at

There isn't one checklist every lender uses when assessing new truck finance. Depending on the application, they can consider a combination of the following.

Your business

Trading history, turnover, cash flow and existing commitments can influence the finance options available.

Your industry experience

Relevant transport or industry experience can support the application, particularly where the business has limited trading history.

The new truck

The lender can consider the vehicle type, purchase price, supplier and intended use.

The body and fit-out

Where a separate body or specialised equipment is being installed, lenders may need details of the complete build.

Purpose of the purchase

Whether the truck is replacing another asset or adding capacity can help explain the commercial reason for the transaction.

Existing finance

Current vehicle and equipment repayments form part of the broader assessment.

Your credit profile

Personal and business credit history can also be considered.

Deposit or trade-in

A deposit isn't always required, although a cash contribution or trade-in may affect the available structure.

The purchase price

The amount being financed is assessed alongside the business position and the truck being purchased.

Recent TAFS deal

A recent TAFS new truck deal

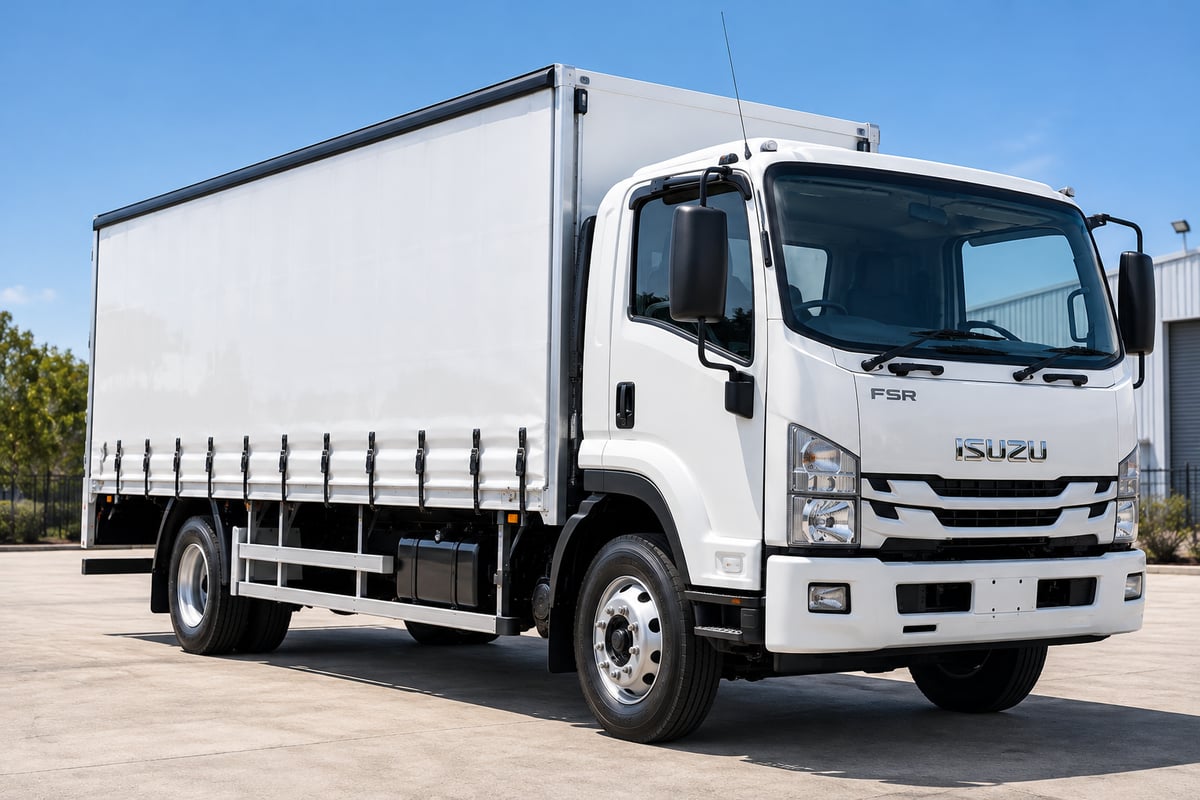
TAFS recently helped finance a 2026 Isuzu FSR truck valued at $195,000.

With a significant commercial vehicle purchase like this, the finance needs to work for more than just the truck itself. The purchase value, business position and how the vehicle will fit into the operation can all influence which lenders are suited to the transaction.

TAFS reviewed the purchase and matched the application with a lender suited to the vehicle and overall deal.

The $195,000 Isuzu FSR was successfully settled, giving the business a current-model commercial truck ready to be put to work.

Deals like this are a good example of how new truck finance can help businesses invest in newer commercial vehicles while structuring the purchase around their wider operation.

  • 2026 Isuzu FSR
  • $195,000 purchase
  • New truck finance
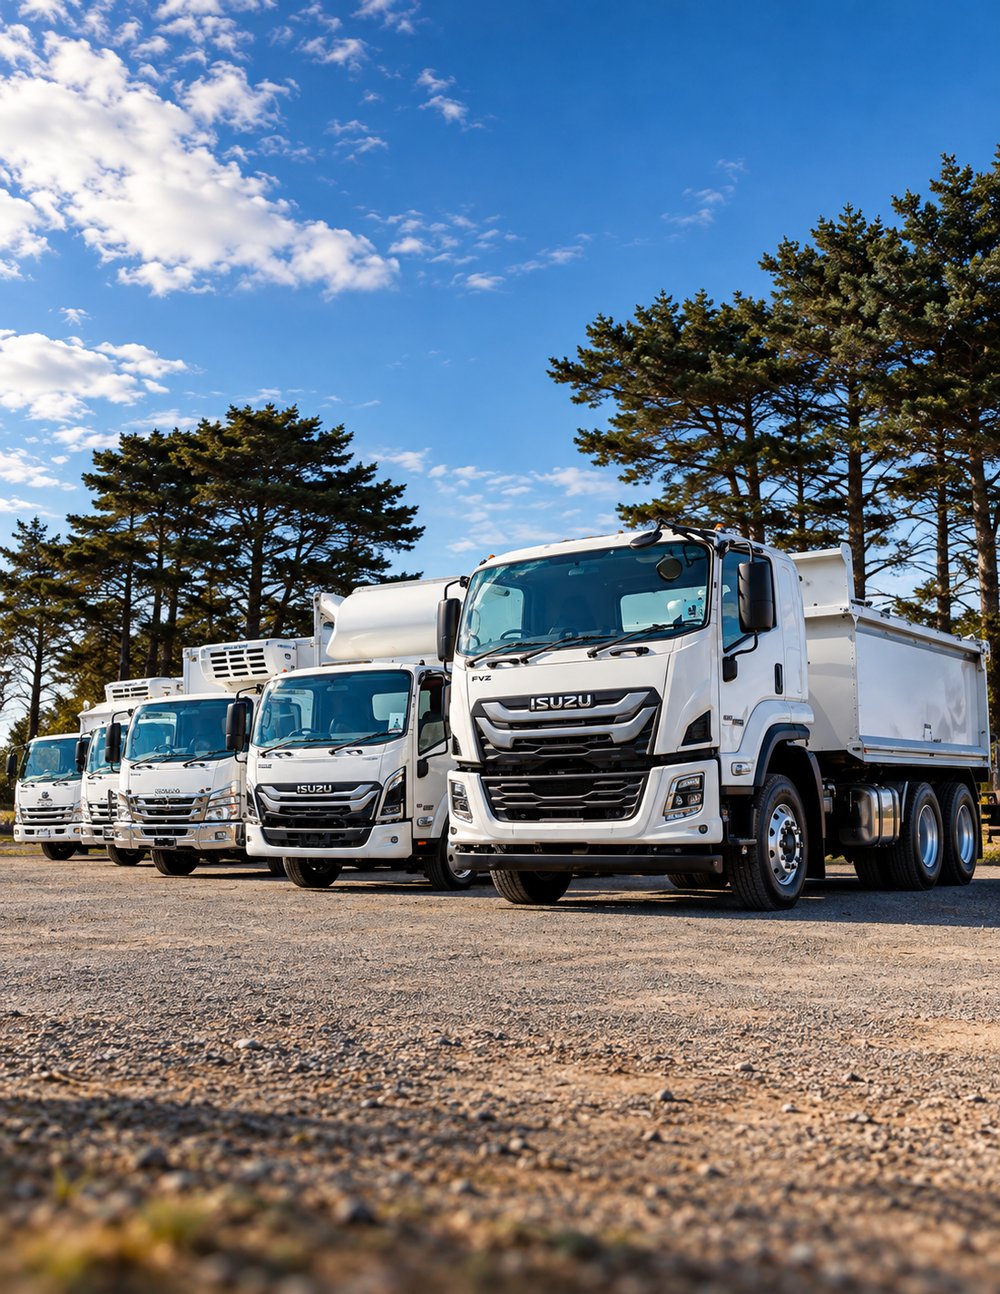
White Isuzu FSR truck in an industrial yard
Why TAFS

Why businesses use TAFS for new truck finance

80+ Lenders

We have access to a broad panel of banks and specialist commercial lenders, giving us more options across different business profiles and truck purchases.

Internal credit team

Applications are reviewed before they're submitted so the lender receives a clear picture of the business, the truck and the reason for the purchase.

93% Client success rate

We focus on matching applications with lenders suited to the transaction and presenting them properly from the beginning.

Commercial asset finance specialists

Our team works with businesses purchasing trucks, trailers, machinery and commercial equipment every day. Whether you're buying a straightforward dealer vehicle or coordinating a cab chassis and specialist body build, we look at the complete transaction before recommending a finance structure.

Trusted lender partners:

Azora Banjo Bizcap Branded Financial Capify CFI Finance Dynamoney Finance One Grenke Judo Bank Lumi MoneyMe
The TAFS Process

How new truck finance works with TAFS

  • Step 1

    Tell us what you're buying

    Send us the truck quote, purchase price and some information about your business. If the truck requires a body or fit-out, send through those details as well.

  • Step 2

    We review the application

    Our team looks at the business, proposed truck, existing commitments and finance requirements.

  • Step 3

    We compare suitable options

    We assess the application against lenders from our panel and identify finance options suited to the transaction.

  • Step 4

    We manage approval and settlement

    Once you've selected an option, we work through the lender requirements, documentation and settlement with the supplier.

FAQ

New Truck Finance FAQs

We don't just send applications out. We structure them properly from the start.

  • Can I finance the full cost of a new truck?

    Potentially. Some businesses may qualify to finance the full purchase price, while others may need or choose to contribute a deposit or trade-in. The available structure depends on the business, truck and lender.

  • Do I need a deposit for a new truck?

    Not necessarily. Lender requirements vary, and a deposit is not required in every transaction. A contribution may still be appropriate depending on the application and how you want to structure the finance.

  • Can I finance a new truck with a new ABN?

    Finance may be available for newer businesses. Where there is limited trading history, lenders can place greater emphasis on industry experience, credit history, expected work and the truck being purchased.

    New ABN Truck Finance →
  • Can a sole trader finance a new truck?

    Yes. Sole traders can apply for new truck finance where the vehicle is being purchased predominantly for business use and the application satisfies lender requirements.

    Sole Trader Truck Finance →
  • Is low-doc finance available for a new truck?

    Low-doc options may be available for some businesses. Requirements vary between lenders and can depend on factors such as ABN age, GST registration, credit profile, purchase price and the amount being financed.

    Low Doc Truck Finance →
  • Can I finance the truck and body fit-out together?

    Potentially. Where the truck and body form part of the completed commercial vehicle, the transaction may be able to be financed together. Where separate suppliers are involved, TAFS will review the quotes and payment arrangements to determine what structure is available.

  • Can I finance a factory-ordered truck?

    Yes, subject to lender requirements. Because delivery can be months after the original order, any finance approval may need to be updated closer to settlement.

  • Can I finance a dealer deposit?

    The treatment of a dealer deposit depends on the transaction and lender. In many cases, the deposit forms part of your contribution while finance covers the remaining balance at settlement. Speak with TAFS before committing a large deposit if you want to understand how it will fit into the finance structure.

  • Can I trade in my current truck?

    Yes. A trade-in can form part of the transaction. If finance is still owing on the current truck, the payout and trade-in value need to be considered together.

  • Can I finance more than one new truck at once?

    Yes. Businesses can apply to finance multiple new trucks as part of a fleet expansion or replacement program. The lender will assess the combined transaction alongside the business's existing commitments.

    Truck Fleet Finance →
  • Can I get approved before the truck arrives?

    Depending on the lender and your circumstances, it may be possible to receive an approval or finance indication before the truck is delivered. Long lead times can mean financial information, credit checks or other approval conditions need to be updated before settlement.

  • How long can I finance a new truck for?

    Finance terms vary depending on the business, truck and lender. A new truck's expected working life can support longer finance terms than may be available for significantly older vehicles, subject to lender policy.

  • How quickly can new truck finance be approved?

    Straightforward applications can move quickly once the required information is available. Timing will depend on the lender, business profile and complexity of the transaction. A completed dealer vehicle may be simpler to settle than a truck involving several suppliers and a custom body build.

Ready to finance your next new truck?

Tell us what you're ordering, when it's expected to arrive and whether any body or equipment is being fitted.

We'll review the complete transaction and compare suitable finance options across our lender panel.