Trusted by 3000+ clients

Light Truck Finance

Finance your next light truck with a team that understands commercial vehicles.

Buying your first light truck, replacing an older vehicle or expanding your delivery fleet, we'll build the finance around your business and the truck you're purchasing.

TAFS works with businesses across transport, logistics, trades, construction, retail and distribution, with access to more than 80 lenders for new and used light truck finance.

Light Truck Finance

Light truck finance for Australian businesses

Light truck finance is commercial asset finance used to purchase smaller commercial trucks for business purposes.

These vehicles are commonly used for local deliveries, freight distribution, trades, construction, landscaping, furniture transport and other commercial operations.

Finance can be arranged for new or used light trucks purchased through dealerships, private sellers or auctions. The options available will depend on your business, the truck being purchased, its age and condition, the purchase price and how it will be used.

TAFS reviews these factors before approaching lenders so the application can be matched with finance options suited to the transaction. See the full range of truck finance options.

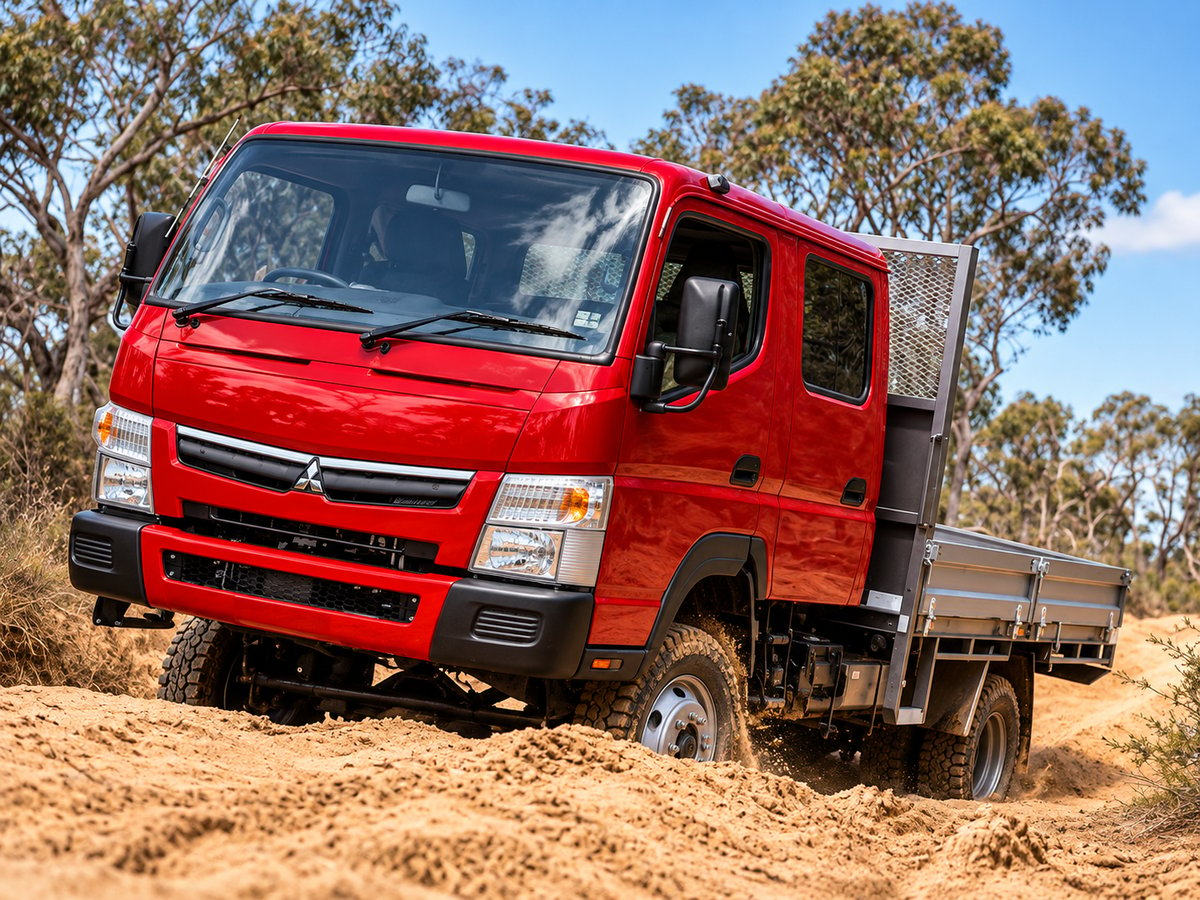
Red Fuso Canter 4x4 crew cab light truck with a dropside tray

Financing a light truck is about finding the right vehicle for the business

Light trucks are used across a wide range of industries, and not every business needs the same vehicle.

A delivery business transporting parcels across metropolitan areas may require a different truck from a landscaping contractor carrying tools, materials and equipment between job sites.

The truck's gross vehicle mass (GVM), payload capacity, body configuration and intended use can all influence which vehicle is suitable.

From a finance perspective, lenders can consider the truck's age, kilometres, condition and purchase price alongside the business's trading history, cash flow and existing commitments.

For an established business replacing a delivery vehicle, the application may be supported by existing operations and financial history. For a business purchasing its first commercial truck, industry experience, expected work and the purpose of the purchase can become more important.

Our team reviews these details before the application is submitted.

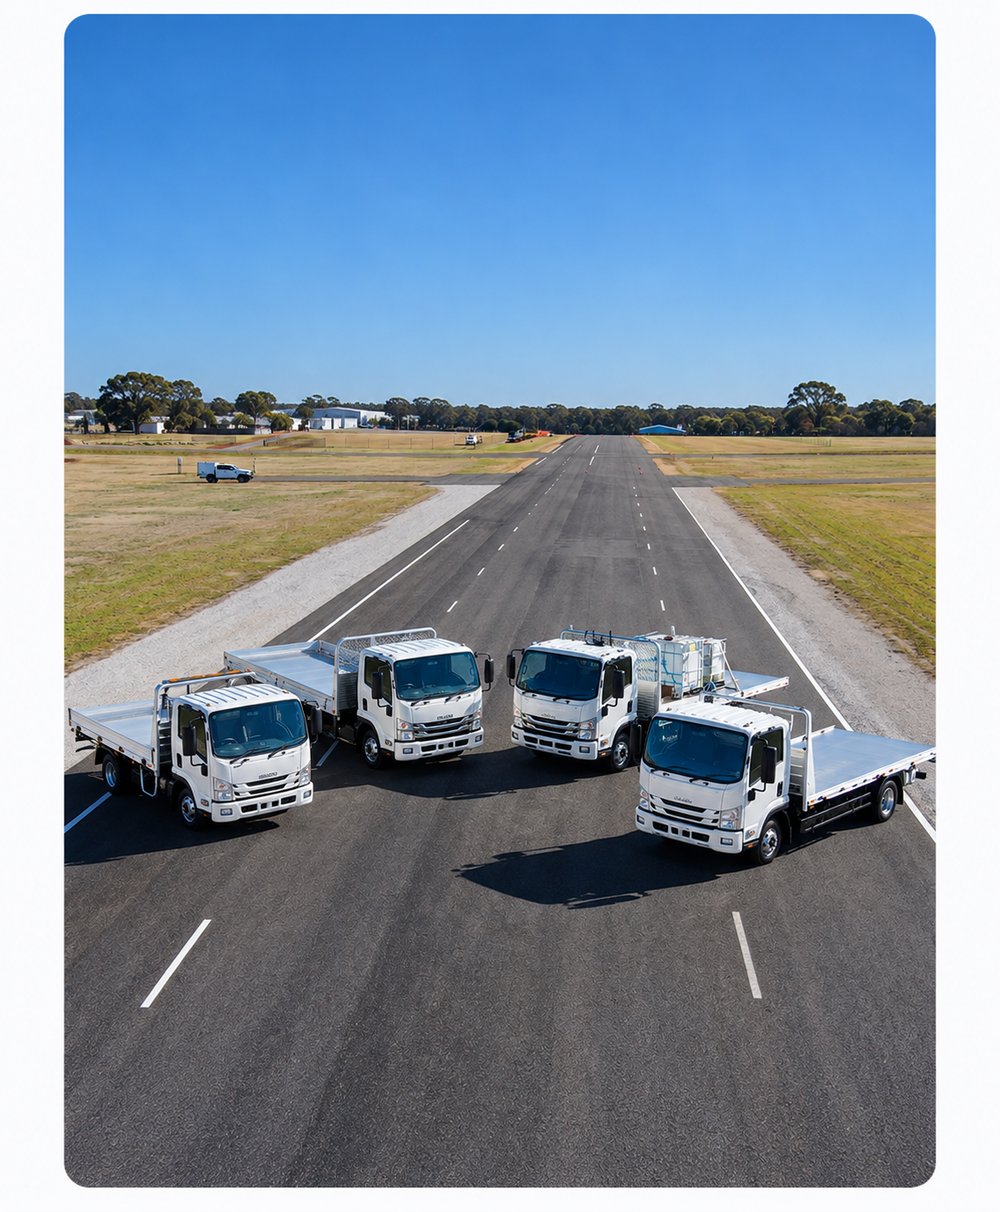
Four Isuzu N-Series light trucks with flat tray bodies lined up

What light trucks can be financed?

TAFS can arrange finance across a broad range of light trucks used in Australian commercial operations. This can include:

  • Light rigid trucks
  • Light-duty cab chassis trucks
  • Light-duty tray trucks
  • Light-duty tipper trucks
  • Light-duty pantech trucks
  • Light-duty refrigerated trucks
  • Light-duty flatbed trucks
  • Small delivery trucks
  • Furniture removal trucks
  • Trade and service trucks
  • New light trucks
  • Used light trucks

We can also help when the truck is being purchased through a dealership, private seller or auction.

  • 15,000+Assets Financed And Businesses Helped
  • $350M+Total Business Funding
  • 80+Lenders To Compare
  • 30+Years Of Business Experience
  • 93%Client Success Rate

Buying your first light truck?

For many businesses, purchasing a light truck is the next step after operating with a ute, van or smaller commercial vehicle.

As the business grows, the existing vehicle may no longer provide enough payload capacity, cargo space or efficiency for the work being performed. A light truck can allow the business to carry larger loads, complete more deliveries or transport equipment that would otherwise require multiple trips.

If you're purchasing your first light truck, lenders can look at the broader business rather than only your previous experience owning commercial trucks. Trading history, industry experience, credit profile, existing work, purchase price and any deposit can all help shape the application.

TAFS works with lenders that assess commercial vehicles differently, allowing us to identify options suited to your circumstances.
Upgrading from a ute or van to a light truck?

Moving from a ute or van into a light truck can be a practical decision for a growing business.

You may need more carrying capacity, a larger enclosed body, additional equipment storage or a vehicle that can handle heavier commercial loads.

For delivery and distribution businesses, a larger truck may reduce the number of trips required to complete a route. For trades and construction businesses, it may allow more tools, equipment and materials to be transported together.

When reviewing the finance, we look at how the new truck fits into your existing operation, including any current vehicle finance and whether the truck is replacing an existing asset. The aim is to structure the purchase around the business's requirements rather than treating it as an ordinary vehicle upgrade.

Adding another light truck to the fleet?

An additional light truck can help a business expand delivery capacity, service new customers or reduce reliance on subcontracted transport. It may also allow different vehicles to be allocated to different routes, locations or types of work.

The finance still needs to fit alongside your existing commitments. We can review your current vehicles, existing finance, the truck you're purchasing and how the additional asset fits into the business before recommending a structure.

For businesses regularly adding or replacing commercial vehicles, looking at the broader fleet position can also help with future finance planning.

New and used light truck finance

TAFS can arrange finance for both new and used light trucks.

A new truck generally provides lenders with clear supplier documentation and a long expected working life.

Used light trucks can vary significantly depending on their age, kilometres, condition and previous commercial use. A relatively new delivery truck with moderate kilometres presents differently from an older vehicle that has spent years operating on demanding delivery schedules.

Older light trucks can still be financeable. The important part is matching the asset with lenders whose policies accommodate its age, value and intended use.

Lenders can consider:

  • Vehicle age
  • Kilometres travelled
  • Truck make and model
  • Overall condition
  • Purchase price
  • Body configuration
  • Proposed finance term
  • Intended commercial use
  • Expected age of the truck when the loan finishes

Understanding GVM and payload when choosing a light truck

Gross vehicle mass (GVM) is the maximum permitted operating weight of a vehicle, including the truck itself, occupants, fuel, equipment and load.

Where light trucks sit

Light trucks are commonly associated with smaller commercial vehicles, although the precise vehicle classification depends on its GVM and configuration.

In Australia, vehicles with a GVM above 4.5 tonnes and up to 8 tonnes fall within the light rigid licence category, subject to the applicable vehicle and licensing rules.

Payload is a separate question

A truck with a larger body doesn't necessarily have a higher usable payload, particularly once additional equipment or a specialised fit-out is installed.

When purchasing a light truck, it helps to understand whether the vehicle can legally and practically carry the loads your business requires.

Why it matters for finance

From a finance perspective, the truck's specifications also help explain why a particular vehicle is being purchased.

Some smaller light-duty trucks have a GVM of 4.5 tonnes or less and may be driven on a standard car licence, depending on the vehicle and driver requirements.

Financing a cab chassis and body fit-out

Not every light truck is purchased as a completed vehicle.

Some businesses purchase a cab chassis and then have a tray, pantech body, refrigerated body, service body or other equipment installed separately.

That can involve multiple suppliers and invoices.

Depending on the lender and transaction, the truck and fit-out may be able to form part of the overall finance structure.

Tell us how the purchase is being put together from the beginning.

That way the complete vehicle can be presented to suitable lenders, rather than the chassis being assessed in isolation.

TAFS can review:

  • The cab chassis purchase
  • Body specifications
  • Installation costs
  • Total project value
  • Supplier invoices for each part of the purchase
  • Whether the body is already fitted to the vehicle

Dealer, private sale and auction purchases

Where you're buying the light truck can influence the finance process.

Dealer purchase

Dealer purchases generally come with established vehicle and supplier documentation, which can help make finance and settlement more straightforward.

Private sale

TAFS can arrange finance when you're purchasing a light truck directly from another business or private seller.

The lender may require additional checks around the seller, ownership and vehicle before settlement.

Auction purchase

Light trucks are regularly sold through commercial vehicle and equipment auctions.

Because auction purchases can move quickly, it can help to understand your likely finance position before bidding. Final approval will still depend on the truck meeting lender requirements.

What lenders look at

There's no single checklist every lender uses when assessing light truck finance. Depending on the application, lenders can consider a combination of the following.

Your business

Trading history, turnover, cash flow and existing financial commitments can influence the finance options available.

Your industry experience

Experience in transport, logistics, trades, construction or another relevant industry can help support the application, particularly for newer businesses.

The light truck

The truck's make, model, age, kilometres, condition and purchase price can affect lender appetite.

The body and configuration

Lenders may consider whether the truck has a tray, pantech body, refrigerated body or another specialised fit-out.

How the truck will be used

The lender can consider whether the vehicle will be used for deliveries, freight distribution, trade work, construction, landscaping or another commercial purpose.

Your credit profile

Personal and business credit history can form part of the assessment.

Deposit or trade-in

A deposit isn't always required, although contributing cash or trading an existing vehicle can strengthen some applications.

Existing finance

Current vehicle and equipment repayments form part of the broader assessment.

Purpose of the purchase

Whether the truck is replacing an existing vehicle or adding capacity can help explain the commercial reason for the transaction.

Recent TAFS deal

A recent TAFS light truck deal

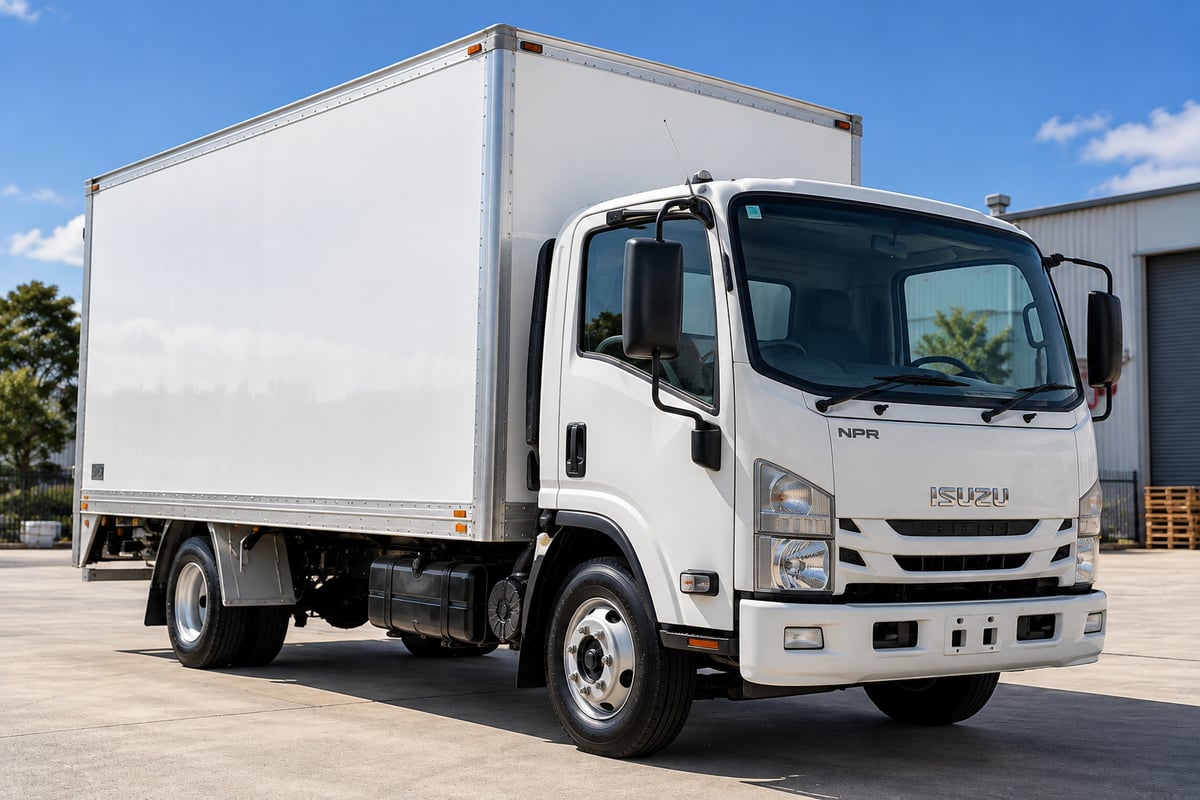
TAFS recently helped finance a 2016 Isuzu NPR Pantech valued at $35,000.

The Isuzu NPR is a practical light commercial truck commonly used for deliveries, freight and other day-to-day business operations, while the pantech body provides enclosed cargo space for goods and equipment.

Because it was a used commercial vehicle, the age, value and configuration of the truck all formed part of finding a lender suited to the transaction.

TAFS matched the purchase with an appropriate lender and the $35,000 Isuzu NPR was successfully settled.

Deals like this are a good example of how light truck finance can support businesses that need more carrying capacity and a purpose-built commercial vehicle without moving into a much larger truck.

  • 2016 Isuzu NPR Pantech
  • $35,000 purchase
  • Used light truck
White Isuzu NPR pantech light truck in an industrial yard
Why TAFS

Why businesses use TAFS for light truck finance

80+ Lenders

We have access to a broad panel of banks and specialist commercial lenders, giving us different options for different trucks and business profiles.

Internal credit team

Applications are reviewed before they're submitted so the lender receives a clear picture of the business, the truck and the purpose of the finance.

93% Client success rate

We focus on matching applications with lenders suited to the transaction and presenting the application properly from the beginning.

Commercial asset finance specialists

Our team works with businesses purchasing trucks, trailers, machinery and commercial equipment every day. We understand that a light truck can be a critical working asset, whether it's used for daily deliveries, trade work or transporting equipment between sites.

Trusted lender partners:

Azora Banjo Bizcap Branded Financial Capify CFI Finance Dynamoney Finance One Grenke Judo Bank Lumi MoneyMe
The TAFS Process

How light truck finance works with TAFS

  • Step 1

    Tell us about the truck

    Send us the light truck details, purchase price and some information about your business. If the truck requires a separate body or fit-out, let us know what's included in the complete purchase.

  • Step 2

    We review the application

    Our team looks at the vehicle, business profile, finance requirements and anything else that may influence lender selection.

  • Step 3

    We find suitable options

    We compare the application against lenders from our panel and identify options suited to the transaction.

  • Step 4

    We manage approval and settlement

    Once you've selected an option, we work through the lender requirements and documentation to get the truck settled.

FAQ

Light Truck Finance FAQs

We don't just send applications out. We structure them properly from the start.

  • Can you finance a used light truck?

    Yes. TAFS can arrange finance for used light trucks across a range of ages and price points. Lenders can consider the vehicle's age, kilometres, condition, purchase price and expected remaining working life when assessing the application.

  • Can I finance an older light truck?

    Potentially. Different lenders have different policies around vehicle age and how old the truck can be at the end of the finance term. Older light trucks may therefore need to be matched with lenders that accommodate the age and type of asset.

    Used Truck Finance →
  • Can I finance a light truck with a new ABN?

    Finance may be available for newer businesses. Where there is limited trading history, lenders may place greater emphasis on previous industry experience, credit history, expected work, the truck being purchased and any contribution towards the deal.

    New ABN Truck Finance →
  • Can a sole trader finance a light truck?

    Yes. Sole traders can apply for commercial light truck finance when the vehicle is predominantly being purchased for business use and the application meets lender requirements.

    Sole Trader Truck Finance →
  • Is low-doc light truck finance available?

    Low-doc options may be available for some applicants. Requirements vary between lenders and can depend on factors such as ABN age, GST registration, asset value, credit history and the amount being financed.

    Low Doc Truck Finance →
  • Do I need a deposit for a light truck?

    Not necessarily. Some businesses may be able to finance the full purchase price, while other applications can benefit from a cash contribution or trade-in. The appropriate structure depends on the business, truck and lender.

  • Can I finance a light truck and body fit-out together?

    Potentially, yes. Where the body is already fitted to the vehicle, the completed truck may be assessed as one commercial asset. Where the truck and body are being supplied separately, the transaction may require a different structure depending on the lender.

  • Can I finance a light truck purchased privately?

    Yes. TAFS can arrange finance for light trucks purchased directly from another business or private seller. Additional seller, ownership and vehicle checks may be required before settlement.

    Private Sale Truck Finance →
  • Can I finance a light truck from an auction?

    Yes, subject to lender requirements. If you're planning to purchase through an auction, discussing finance before bidding can help you understand your likely position. The lender will still need to approve the final vehicle.

    Auction Truck Finance →
  • Can I get finance before I've found the light truck?

    Depending on the lender and your circumstances, it may be possible to obtain an indication or conditional approval before choosing the final truck. The vehicle will still need to satisfy lender requirements before settlement.

  • Can I finance a light truck with a car licence?

    Finance eligibility and driver licensing are separate considerations. Some light-duty trucks with a GVM of 4.5 tonnes or less may be driven on a standard car licence in Australia. Heavier vehicles can require an appropriate truck licence. The vehicle's specifications and the applicable licensing requirements should be checked before purchasing.

  • How long can I finance a light truck for?

    Finance terms vary according to the applicant and asset. The truck's age, condition and expected working life can influence the available finance term, particularly for used vehicles.

  • How quickly can light truck finance be approved?

    Straightforward applications can move quickly once the required information is available. Timing will depend on the lender, complexity of the application, purchase type and whether additional seller or vehicle checks are required.

Ready to finance your next light truck?

Tell us what you're buying and how the truck will be used in your business.

We'll review the vehicle, understand your requirements and compare suitable finance options across our lender panel.