Business Chattel Mortgage for Equipment in Australia
Read time: 22 min
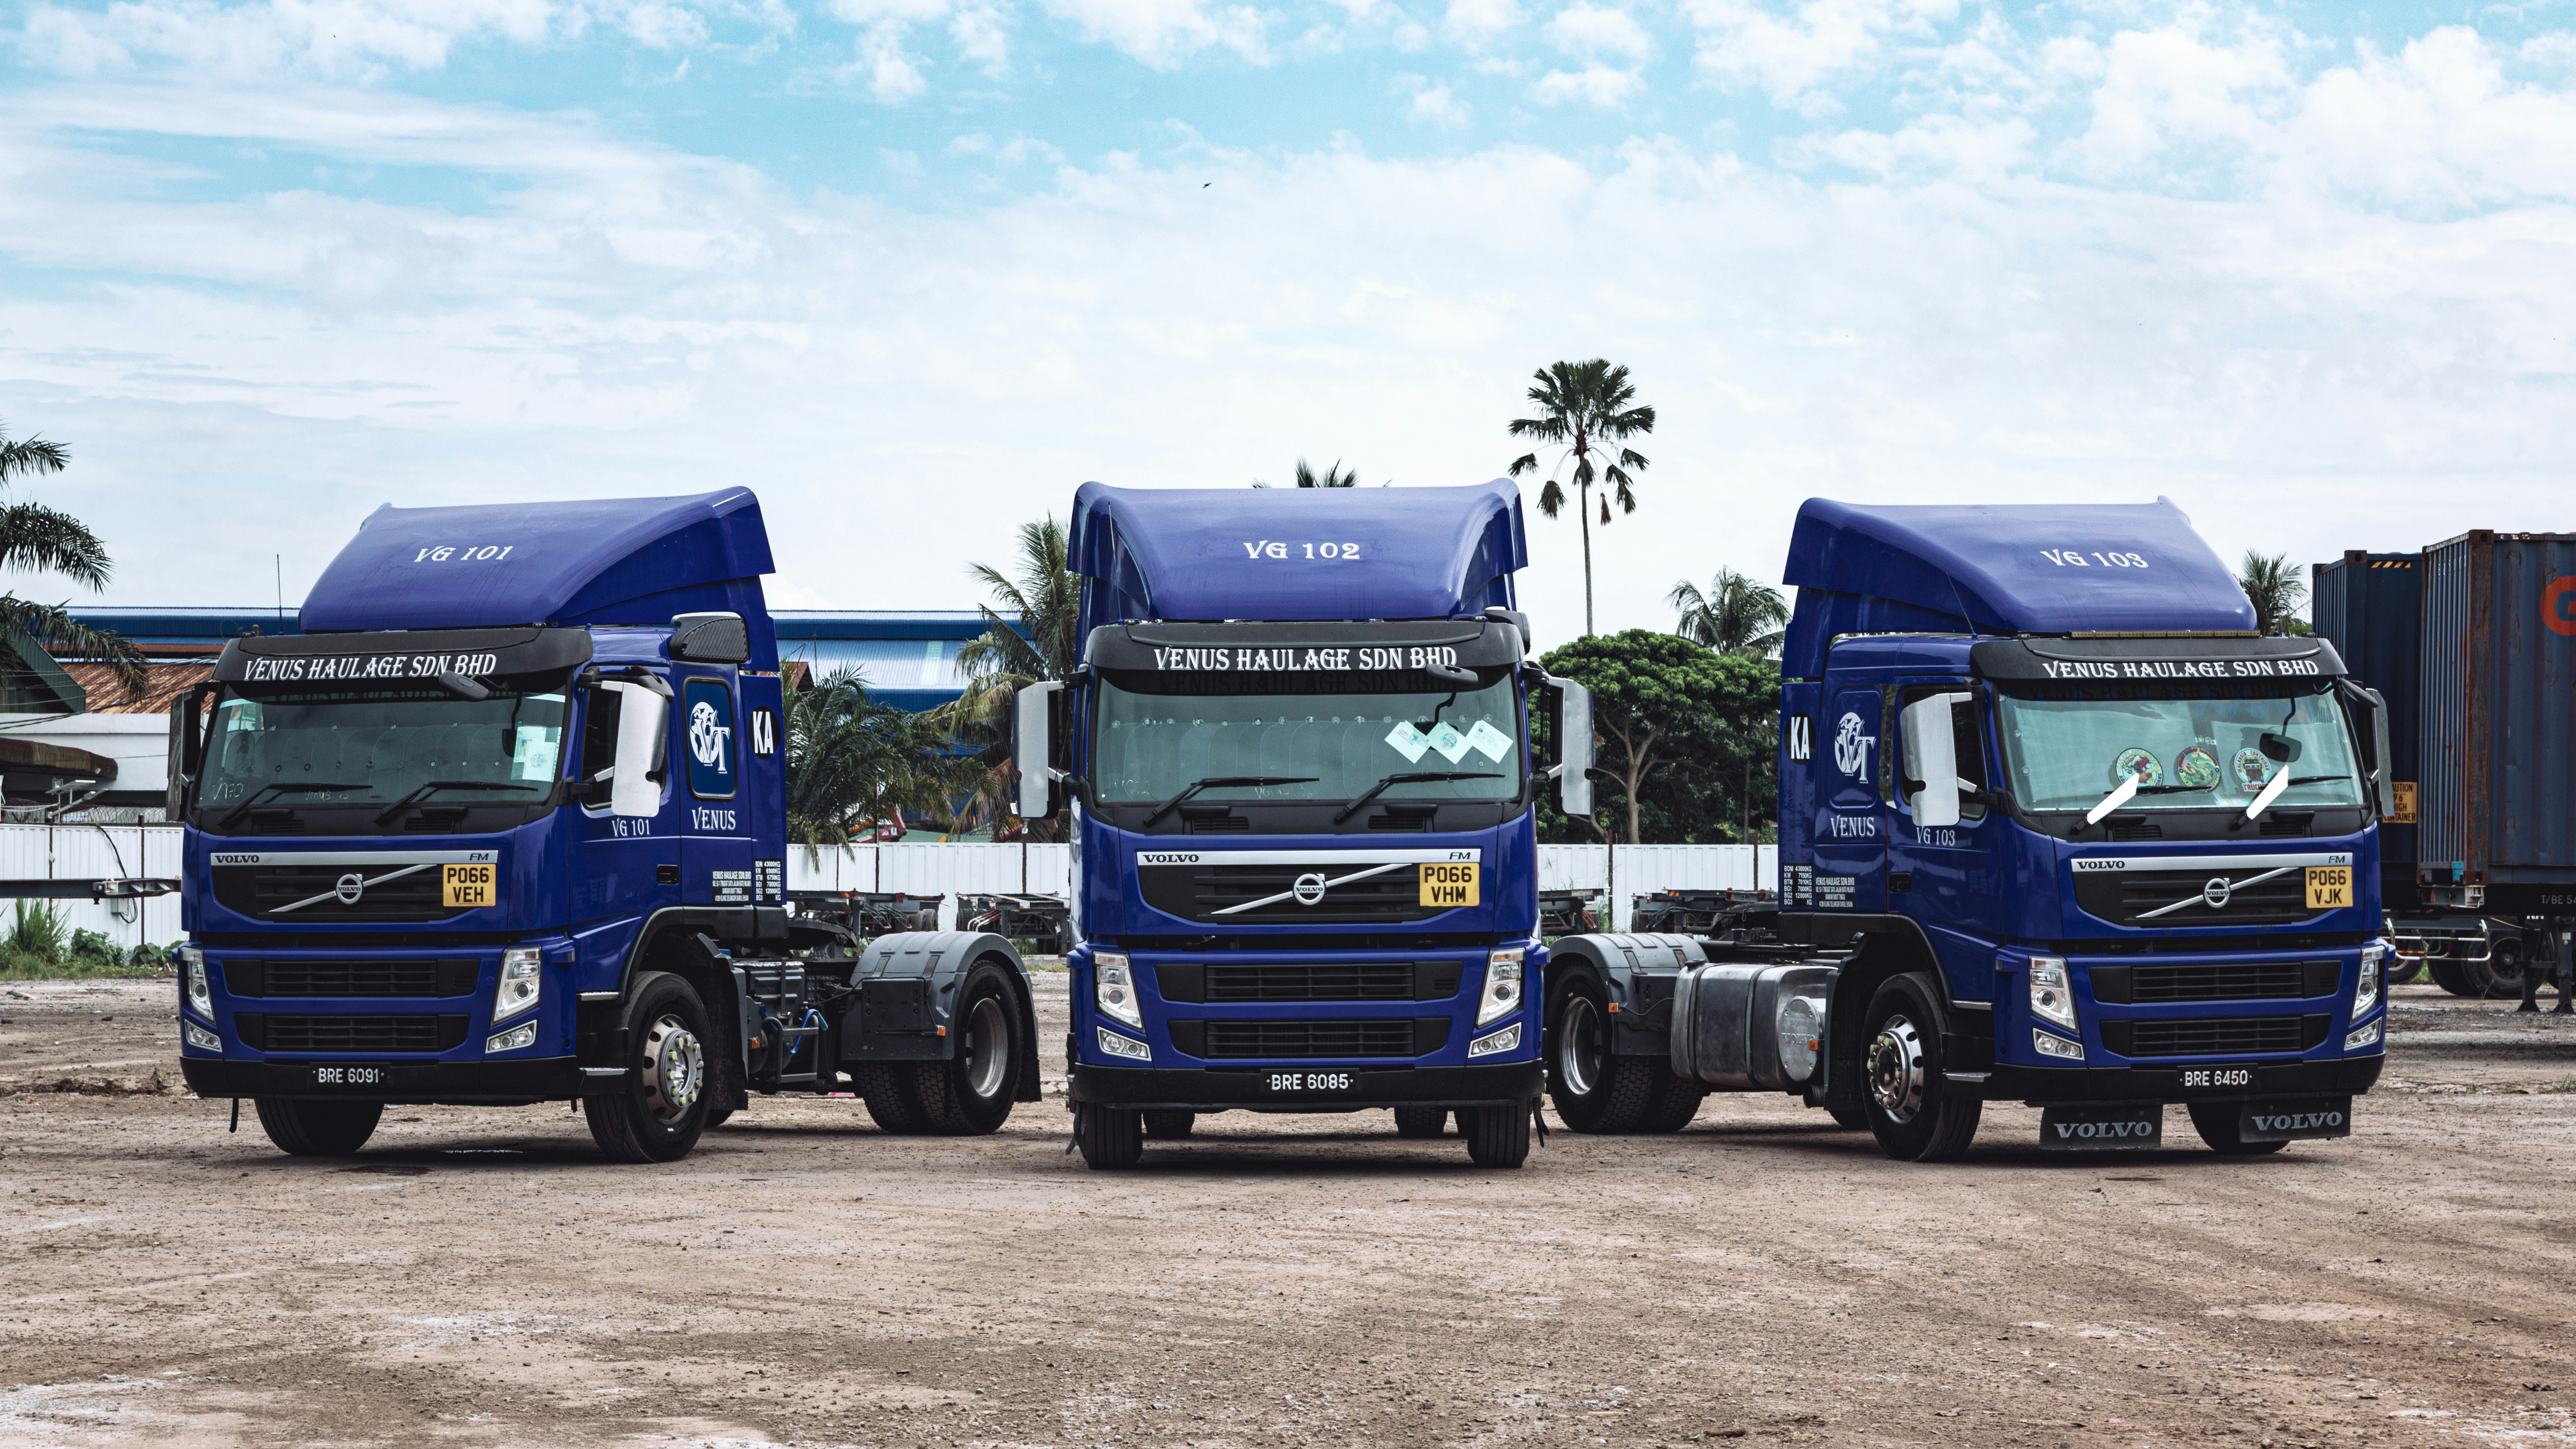
A chattel mortgage is one of the main ways Australian businesses finance vehicles, machinery and commercial equipment while owning the asset from the day the finance settles.
Instead of paying the entire purchase price upfront, the business borrows against the equipment and repays the finance over an agreed term. The lender registers security over the asset while the loan remains outstanding.
For businesses that intend to own and use equipment for the long term, this can provide a straightforward alternative to structures where the finance provider owns the equipment during the agreement.
The Asset Finance Shop (TAFS) primarily arranges chattel mortgage finance for commercial assets. Through access to more than 80 bank and non-bank lenders, TAFS can structure finance around the asset, business, available deposit, preferred term and cash flow requirements.
This guide explains how a business chattel mortgage works, what can be financed, how tax treatment may apply and how chattel mortgage compares with hire purchase and rent to own.
What Is a Chattel Mortgage?
A chattel mortgage is a commercial loan used to purchase a business asset.
The word chattel refers to the movable asset being financed.
This might be a:
- Truck
- Ute
- Van
- Excavator
- Skid steer
- Tractor
- Forklift
- Manufacturing machine
- Piece of commercial equipment
Under a chattel mortgage:
- Your business purchases the asset
- Your business owns the asset from settlement
- The lender provides the finance
- The lender registers security over the asset
- You make agreed repayments over the finance term
- A deposit or trade-in can potentially be included
- A balloon payment may potentially be used
- The lender removes its security after the finance is repaid
This ownership structure is one of the main differences between a chattel mortgage and some other forms of equipment financing.
How Does a Chattel Mortgage Work?
The process generally begins with the equipment your business wants to purchase.
1. Choose the Equipment
The asset can potentially be purchased through:
- A dealership
- Equipment supplier
- Private seller
- Auction
Both new and used commercial equipment can be considered, subject to lender requirements.
2. Determine the Purchase Price
For example:
Equipment price: $180,000
The business then decides whether it wants to:
- Finance the full eligible purchase price
- Contribute a cash deposit
- Use trade-in equity
- Include other eligible costs where the lender allows it
3. Structure the Finance
A commercial finance broker can help structure:
- Finance amount
- Deposit
- Finance term
- Repayments
- Balloon
- Lender
For example:
Equipment price: $180,000
Deposit: $20,000
Finance amount: $160,000
Term: 5 years
A balloon may also be included where appropriate.
4. The Business Purchases the Asset
Once settlement occurs, the business owns the equipment.
The lender registers security over it while the finance remains outstanding.
5. The Business Makes Repayments
Repayments are made over the agreed finance term.
The exact repayment depends on factors including:
- Amount financed
- Interest rate
- Term
- Balloon
- Fees
6. The Loan Is Repaid
Once the finance has been fully repaid, the lender removes its security interest over the asset.
The business already owns the equipment, so there is not a separate ownership transfer at the end in the same way there may be under other structures.
What Equipment Can Be Purchased With a Chattel Mortgage?
A chattel mortgage can be used across a broad range of industries.
Trucks and Commercial Vehicles
TAFS can arrange finance for eligible:
- Prime movers
- Rigid trucks
- Tippers
- Refrigerated trucks
- Crane trucks
- Tilt trays
- Trailers
- Utes
- Vans
- Service vehicles
Earthmoving and Construction Machinery
This can include:
- Excavators
- Mini excavators
- Skid steers
- Posi-tracks
- Loaders
- Rollers
- Graders
- Dozers
- Attachments
Agricultural Machinery
This can include:
- Tractors
- Harvesters
- Headers
- Seeders
- Balers
- Agricultural implements
Materials Handling Equipment
This can include:
- Forklifts
- Telehandlers
- Access equipment
- Scissor lifts
Manufacturing Equipment
This can include:
- CNC machinery
- Lathes
- Presses
- Fabrication equipment
- Packaging equipment
- Production machinery
Other Commercial Equipment
Selected lenders can consider other identifiable business assets that are being purchased for commercial use.
The available finance depends on the asset and lender criteria.
Why Do Businesses Use a Chattel Mortgage?
The main attraction is the combination of asset ownership and structured repayments.
The business gets the equipment it needs now without necessarily removing the full purchase price from working capital.
For example, consider a contractor purchasing a:
$200,000 excavator
Paying cash means $200,000 leaves the business immediately.
Financing the excavator may allow more of that money to remain available for:
- Wages
- Fuel
- Materials
- Insurance
- Transport
- Repairs
- Suppliers
- Tax
- Project costs
- Unexpected expenses
The business pays interest for using the finance, so the decision should compare the finance cost with the value of keeping cash available.
Who Owns the Equipment Under a Chattel Mortgage?
The business does.
This is one of the most important parts of the chattel mortgage definition.
Once settlement occurs:
Business = owner
Lender = secured financier
The lender does not own the equipment in the same way a provider may under a hire purchase or rent-to-own arrangement.
Instead, the lender registers security over the asset until the finance has been repaid.
What Does the Lender's Security Mean?
The financed equipment acts as security for the loan.
For example, if a business finances an excavator:
- The business owns the excavator
- The lender registers its financial interest over the excavator
- The business operates the excavator
- The business makes the agreed repayments
- The security is removed after the finance has been repaid
This is why the lender assesses both:
- The business applying for finance
- The equipment being purchased
Chattel Mortgage vs Hire Purchase
The main difference between a chattel mortgage and traditional hire purchase is ownership.
Chattel Mortgage
Under a chattel mortgage:
- The business purchases the equipment
- The business owns it from settlement
- The lender provides the finance
- The lender holds security over the equipment
- The loan is repaid over time
Hire Purchase
Under a traditional hire purchase agreement:
- The finance provider generally owns the equipment during the agreement
- The business uses the equipment
- The business makes agreed payments
- Ownership generally transfers according to the agreement after the required payments have been completed
The exact legal and financial terms depend on the specific agreement.
TAFS primarily arranges chattel mortgage finance rather than hire purchase.
Chattel Mortgage vs Rent to Own
Rent-to-own follows another ownership model.
Chattel Mortgage
The business owns the equipment from settlement.
Rent to Own
Under a typical rent-to-own arrangement:
- The provider generally owns the equipment initially
- The business makes rental payments
- The business uses the equipment during the rental period
- Ownership may transfer later if the conditions of the agreement are satisfied
For businesses comparing rent to own with a chattel mortgage, the monthly payment should not be the only consideration.
Compare:
- Who owns the equipment
- When ownership begins
- Deposit
- Regular repayments
- Total cost
- End-of-term payment
- End-of-term ownership
- Tax treatment
- Replacement plans
- Expected time using the equipment
TAFS does not position rent to own as its primary equipment finance product.
Chattel Mortgage vs Hire Purchase vs Rent to Own
|
Feature |
Chattel Mortgage |
Hire Purchase |
Rent to Own |
|
Business owns asset from settlement |
Yes |
Generally no |
Generally no |
|
Initial owner |
Business |
Finance provider |
Provider |
|
Regular payments |
Finance repayments |
Hire purchase payments |
Rental payments |
|
Ownership at end |
Business already owns asset |
Generally transfers under agreement |
May transfer under agreement |
|
Lender/provider interest |
Lender holds security |
Depends on agreement |
Provider generally owns equipment |
|
Deposit may be available |
Yes |
Depends on agreement |
Depends on agreement |
|
Balloon may be available |
Yes |
Depends on agreement |
Structure differs |
|
Main equipment finance structure arranged by TAFS |
Yes |
No |
No |
The actual legal, accounting and tax treatment depends on the specific finance agreement.
Is a Chattel Mortgage Better Than Hire Purchase?
Neither product is automatically better for every business.
A chattel mortgage may suit a business that wants to:
- Own the equipment immediately
- Keep the asset long term
- Spread the purchase price over time
- Preserve working capital
- Use a deposit
- Use trade-in equity
- Potentially include a balloon
Hire purchase follows a different ownership structure.
When comparing the two, look beyond the monthly repayment.
Consider:
- Ownership
- Total finance cost
- Deposit
- End-of-term obligations
- Cash flow
- Tax treatment
- Expected asset life
Because TAFS primarily arranges chattel mortgage finance, businesses considering hire purchase should review the specific agreement and discuss tax treatment with their accountant.
Is a Chattel Mortgage Better Than Rent to Own?
It depends on what the business wants from the asset.
If the business intends to purchase equipment and own it from the beginning, a chattel mortgage provides a straightforward ownership structure.
Rent to own may suit different circumstances because ownership generally remains with the provider initially.
Consider a business purchasing a machine it expects to operate for eight years.
Owning the equipment from settlement may be important.
Another business might have different requirements around:
- Cash flow
- Asset replacement
- Ownership
- Short-term use
The strongest option should be determined by the total commercial outcome, not simply which product produces the smallest advertised repayment.
Is a Chattel Mortgage Tax Deductible?
Parts of a chattel mortgage transaction may be tax deductible, but the entire finance repayment should not automatically be treated as one deduction.
A normal repayment contains two main components:
Principal
This reduces the amount originally borrowed.
Interest
This is the lender's charge for providing the finance.
Eligible business-use interest may potentially be deductible.
The asset itself may then be treated separately for:
- Depreciation
- Applicable capital allowance rules
- GST
The exact treatment depends on the business, asset and how it is used.
Speak with your accountant before making a finance decision based on tax outcomes.
Is Chattel Mortgage Interest Tax Deductible?
Eligible interest associated with an income-producing business asset may potentially be deductible.
For example, a business may finance an excavator that is used entirely to generate business income.
The interest component of the finance may potentially form part of the business's deductible expenses.
Where an asset is partly used privately, the tax treatment may need to be adjusted according to business use.
Your accountant should confirm the appropriate claim.
Is the Full Chattel Mortgage Repayment Deductible?
Generally, no.
This is a common misunderstanding.
Imagine the business makes a:
$4,000 monthly repayment
That does not automatically mean the business claims:
$4,000 per month as a finance expense
The repayment includes principal and interest.
Principal reduces the loan balance.
Eligible interest may be treated differently.
The asset itself is considered separately.
Can You Claim GST on Equipment Bought With a Chattel Mortgage?
Potentially.
A GST-registered business may be able to claim an eligible GST credit on the business-use portion of the asset purchase where the applicable requirements are satisfied.
The position can depend on factors including:
- GST registration
- Whether the seller charged GST
- Business-use percentage
- Type of purchase
- Invoice
- Specific tax circumstances
The GST treatment is separate from the loan repayment.
Dealer Purchase vs Private Sale GST
The seller can make a difference.
Dealer or Business Seller
Where the seller charges GST, an eligible GST-registered business may potentially have a GST credit available.
Private Seller
A private seller may not charge GST.
If no GST is charged on the sale, there may be no purchase GST credit available.
The equipment can still potentially be financed.
Finance eligibility and GST treatment are separate issues.
Can Depreciation Be Claimed?
Potentially.
Because the business owns an asset purchased under a chattel mortgage, eligible depreciation or other applicable capital allowance treatment may apply.
The outcome can depend on:
- Equipment type
- Purchase price
- Date first used
- Business-use percentage
- Applicable tax rules
- Business circumstances
The loan term does not automatically determine how the equipment is depreciated.
A machine financed over five years does not necessarily have a five-year depreciation period.
Finance and tax accounting are separate calculations.
Does a Balloon Payment Increase Tax Deductions?
Not automatically.
A balloon is an amount of principal remaining at the end of the finance term.
For example:
Finance amount: $150,000
Term: 5 years
Balloon: $30,000
Regular repayments are generally lower because $30,000 remains outstanding.
But the balloon itself does not automatically create an additional tax deduction.
A larger balloon can affect:
- Monthly repayments
- Principal outstanding
- Total interest
Your accountant should advise on the tax treatment.
Why Use a Balloon Payment?
A balloon can be useful where the business wants to reduce regular repayments.
That can leave more monthly cash available for:
- Wages
- Materials
- Fuel
- Suppliers
- Other business costs
The balloon needs to make commercial sense relative to the expected future value of the equipment.
For example, leaving a very large final payment on an asset expected to have little value by the end of the finance term may create unnecessary risk.
Do I Need a Deposit?
Not in every application.
Deposit requirements depend on:
- Business history
- Credit profile
- Equipment
- Asset age
- Asset value
- Finance amount
- Documentation
- Lender
A deposit can reduce:
- Amount financed
- Repayment
- Interest cost
However, contributing a deposit also removes cash from the business.
The best structure should consider working capital as well as the repayment.
Can Trade-In Equity Be Used?
Potentially.
If the business is replacing an existing asset, available equity may contribute toward the new equipment.
For example:
Trade-in value: $90,000
Existing finance payout: $40,000
Potential equity:
$50,000
That $50,000 may be applied toward the replacement asset.
The existing lender can be paid out as part of settlement.
Can the Full Equipment Price Be Financed?
Potentially.
Selected applications may qualify to finance the full eligible purchase price.
The lender may assess:
- Business history
- Credit position
- Repayment capacity
- Equipment value
- Purchase price
- Existing debts
- Available documents
The purchase price also needs to make sense relative to the lender's assessment of the asset's value.
Can Sole Traders Use a Chattel Mortgage?
Yes.
Sole traders can apply for a chattel mortgage for eligible business vehicles, machinery and equipment.
The lender may consider:
- ABN history
- Time trading
- Industry experience
- Business bank statements
- Business income
- Credit history
- Existing debts
- Asset being purchased
The asset should generally be purchased for an income-producing business purpose.
Can a New ABN Get a Chattel Mortgage?
Potentially.
There is no single minimum ABN age across every commercial asset finance lender.
Selected lenders can consider newer businesses based on factors including:
- Previous industry experience
- Current work
- Expected work
- Bank statements
- Financial position
- Credit history
- Deposit
- Equipment
A new ABN does not automatically mean the applicant is new to the industry.
For example:
ABN age: 8 months
Earthmoving experience: 12 years
Equipment: Excavator
Current work: Existing civil projects
That complete background should be included in the application.
Can You Get a Low Doc Chattel Mortgage?
Potentially.
Selected lenders can assess eligible low doc applications without requiring full financial statements in every case.
The lender may instead use:
- Recent business bank statements
- ABN information
- Credit history
- Industry experience
- Existing finance
- Current work
- Asset information
Low doc does not mean no assessment.
The lender still needs to understand the business and whether it can support the proposed repayment.
Can Used Equipment Be Financed?
Yes.
Used business equipment can be financed through selected lenders.
The lender may consider:
- Age
- Condition
- Kilometres
- Operating hours
- Purchase price
- Market value
- Expected working life
Older equipment can sometimes result in:
- Fewer lender options
- Shorter finance terms
- Lower balloon options
- Inspection requirements
- Valuation requirements
Can Private-Sale Equipment Be Financed?
Yes, through selected lenders.
A business does not necessarily need to purchase equipment through a dealer.
Private-sale finance may require additional checks around:
- Seller identity
- Ownership
- Serial number or VIN
- Existing security
- Purchase price
- Market value
- Condition
An inspection or valuation may also be required.
Can Auction Equipment Be Financed?
Yes, through selected lenders.
An initial finance assessment before an auction can help establish:
- Approximate borrowing position
- Deposit requirements
- Suitable asset age
- Finance term
- Lender requirements
Final approval remains subject to the equipment purchased.
What Does a Lender Assess for Chattel Mortgage Finance?
Commercial equipment financing involves assessment of both the business and the asset.
1. ABN and Trading History
The lender may look at:
- ABN age
- Time trading
- Business structure
- Previous business history
2. Industry Experience
Relevant experience can be particularly important for newer businesses.
3. Business Income
Depending on the lender, this may be assessed using:
- Bank statements
- BAS
- Financial statements
- Tax returns
- Current contracts
- Customer income
4. Existing Debt
This can include:
- Vehicle finance
- Equipment finance
- Business loans
- Credit cards
- ATO obligations
5. Credit History
The lender may consider:
- Current repayment conduct
- Past defaults
- Credit enquiries
- Current debts
6. The Equipment
This can include:
- Asset type
- Age
- Condition
- Purchase price
- Market value
- Expected working life
7. Repayment Capacity
Ultimately, the lender needs to determine whether the proposed finance fits the financial position of the business.
What Documents Do You Need?
The exact documents depend on the lender and application.
For an initial assessment, useful information may include:
- Driver's licence
- ABN details
- Business structure
- Recent bank statements
- Existing finance
- Asset details
- Purchase price
- Seller information
Some applications may also require:
- BAS
- Financial statements
- Tax returns
- Contracts
- Accountant information
- Assets and liabilities
- Equipment valuation
- Inspection
TAFS can determine which documents the selected lender actually requires.
How Fast Can a Chattel Mortgage Be Approved?
Straightforward commercial asset finance applications can be approved in as little as 24 hours once the required information is available.
Approval may take longer where the application includes:
- New ABN
- Limited documentation
- Previous credit issues
- ATO debt
- Older equipment
- Private sale
- Specialised equipment
- Valuation
- Inspection
Approval and settlement are also separate stages.
The finance may be approved while final asset or seller checks are still being completed.
How Should You Compare Chattel Mortgage Offers?
Do not compare only the advertised interest rate.
Look at the entire finance structure.
Compare:
- Purchase price
- Deposit
- Finance amount
- Interest rate
- Finance term
- Monthly repayment
- Balloon
- Establishment fees
- Other charges
- Early payout conditions
- Total estimated finance cost
For example, a lower repayment may simply be the result of:
- Longer finance term
- Larger balloon
That does not automatically mean the finance is cheaper.
What Is the Best Chattel Mortgage Interest Rate?
There is no single rate available to every Australian business.
Pricing can depend on:
- ABN history
- Trading history
- Credit profile
- Asset type
- Asset age
- Finance amount
- Deposit
- Finance term
- Balloon
- Documentation
- Lender
The goal should be to find a competitive finance structure from a lender whose criteria suit the application.
Why Use a Broker for a Chattel Mortgage?
Applying directly to one lender means the business is assessed against that lender's policy.
A specialised asset finance broker can compare the application against multiple lender criteria.
For example:
Lender A
May suit established businesses with full financials.
Lender B
May provide a low doc pathway.
Lender C
May consider a newer ABN with strong industry experience.
Lender D
May be more comfortable financing older used equipment.
Lender E
May accept private-sale machinery.
The business has not changed between those lenders.
Their policies have.
TAFS has access to more than 80 bank and non-bank lenders.
How TAFS Arranges a Chattel Mortgage
Step 1: Review the Business
TAFS assesses:
- ABN history
- Trading history
- Industry experience
- Available documentation
- Existing finance
- Credit profile
Step 2: Review the Equipment
TAFS looks at:
- Asset type
- New or used
- Age
- Purchase price
- Seller
- Intended business use
Step 3: Soft Credit Check
TAFS starts with a soft credit check before the formal lender application.
Step 4: Internal Credit Review
The internal credit team pre-vets the application against lender requirements.
Step 5: Compare Suitable Lenders
TAFS compares the application against suitable options from its panel of more than 80 bank and non-bank lenders.
Step 6: Structure the Finance
This can include:
- Deposit
- Trade-in
- Amount financed
- Finance term
- Repayment
- Balloon
Step 7: One Formal Application
Once an appropriate lender and structure are selected, the formal application is submitted.
Step 8: Approval and Settlement
TAFS coordinates the remaining lender, supplier and settlement requirements.
Chattel Mortgage Equipment Finance Checklist
Before applying, prepare information around:
|
Area |
Information |
|
Business |
ABN and business structure |
|
Identity |
Driver's licence |
|
Trading history |
Time in business |
|
Banking |
Recent business bank statements |
|
Experience |
Relevant industry background |
|
Existing finance |
Vehicle, equipment and business loans |
|
Asset |
Make, model, year and description |
|
Purchase |
Price and seller |
|
Deposit |
Cash contribution if applicable |
|
Trade-in |
Value and finance payout |
|
Settlement |
Invoice and asset identification |
Not every lender requires every item.
Frequently Asked Questions
What Is a Chattel Mortgage?
A chattel mortgage is a commercial loan used to purchase a business asset.
The business owns the asset from settlement while the lender registers security over it until the finance has been repaid.
What Does Chattel Mean?
Chattel refers to the movable asset being financed.
This can include a vehicle, truck, machine or other commercial equipment.
Who Owns the Asset Under a Chattel Mortgage?
The business owns the asset from settlement.
The lender holds security over it while the loan remains outstanding.
Can a Chattel Mortgage Be Used for Equipment?
Yes.
Chattel mortgage equipment financing can be used for eligible commercial vehicles, machinery and business equipment.
Is a Chattel Mortgage Tax Deductible?
Parts of the transaction may potentially be deductible.
Eligible business-use interest may be deductible, while depreciation and GST are treated separately.
The complete finance repayment should not automatically be treated as one deduction.
Is Chattel Mortgage Interest Deductible?
Eligible interest relating to business use may potentially be deductible.
Speak with your accountant about your specific circumstances.
Can GST Be Claimed on a Chattel Mortgage?
Potentially.
An eligible GST-registered business may be able to claim a GST credit on the business-use portion of the purchase where the relevant requirements are satisfied.
Can You Claim Depreciation?
Potentially.
Because the business owns the asset, eligible depreciation or other applicable capital allowance treatment may apply.
What Is the Difference Between Chattel Mortgage and Hire Purchase?
The main difference is ownership.
Under a chattel mortgage, the business owns the asset from settlement.
Under traditional hire purchase, the finance provider generally owns the asset during the agreement and ownership generally transfers later according to the contract.
What Is the Difference Between Chattel Mortgage and Rent to Own?
With a chattel mortgage, the business owns the equipment from settlement.
Under a typical rent-to-own arrangement, the provider generally retains ownership initially, with ownership potentially transferring later.
Is Chattel Mortgage Better Than Hire Purchase?
It depends on the business.
A chattel mortgage may suit businesses that want immediate ownership and intend to retain the equipment.
Compare the full commercial and tax outcome rather than only repayments.
Is Chattel Mortgage Better Than Rent to Own?
It depends on the required ownership structure, total cost, cash flow and long-term plans for the asset.
TAFS primarily arranges chattel mortgage finance.
Can Sole Traders Use a Chattel Mortgage?
Yes.
Sole traders can apply for chattel mortgage finance for eligible business assets, subject to lender approval.
Can a New ABN Get a Chattel Mortgage?
Potentially.
Selected lenders consider newer businesses based on industry experience, current work, financial position, credit history and the asset.
Can I Get a Low Doc Chattel Mortgage?
Potentially.
Selected lenders can assess eligible applications using recent bank statements and other current business information instead of full financial statements.
Can Used Equipment Be Financed?
Yes.
Used commercial equipment can be financed through selected lenders, subject to age, condition and value requirements.
Can I Purchase Equipment Privately?
Yes, through selected lenders.
Additional seller and equipment checks may be required.
Can Auction Equipment Be Financed?
Potentially.
Selected lenders finance eligible auction purchases, and an initial assessment can be completed before bidding.
Do I Need a Deposit?
Not always.
Deposit requirements depend on the business, asset and lender.
Can I Finance 100% of the Equipment Purchase?
Potentially.
Selected applicants may qualify for finance covering the full eligible purchase price.
Can a Chattel Mortgage Have a Balloon?
Potentially.
A balloon can reduce regular repayments but leaves a larger amount outstanding at the end of the finance term.
Does a Balloon Increase My Tax Deduction?
Not automatically.
A balloon changes how principal is repaid and does not itself create an additional deduction.
Does TAFS Offer Hire Purchase or Rent to Own?
TAFS primarily arranges chattel mortgage finance for eligible commercial vehicles, machinery and equipment.
Hire purchase and rent to own are discussed here so businesses can understand the differences between common equipment financing structures.
How Many Lenders Can TAFS Compare?
TAFS has access to more than 80 bank and non-bank lenders.
Does TAFS Apply to All of Those Lenders?
No.
TAFS assesses the business and asset first, compares relevant lender criteria and then submits the formal application to the selected lender.
Arrange a Business Chattel Mortgage With TAFS
A chattel mortgage can give an Australian business immediate ownership of the commercial vehicle, machinery or equipment it needs while spreading the purchase cost over an agreed finance term.
The right structure should consider more than the monthly repayment.
Purchase price, deposit, trade-in equity, finance term, balloon, working capital, total finance cost and the expected working life of the equipment should all form part of the decision.
TAFS can review your business, asset and available documentation before comparing suitable chattel mortgage options through access to more than 80 bank and non-bank lenders.
The Asset Finance Shop (TAFS) is a commercial asset finance brokerage based in Sydney.
Information on this page is general in nature and doesn't take your personal circumstances into account. Speak to a TAFS broker for options tailored to your business, and to your accountant regarding tax treatment.